RAA ACCREDITED VALUERS (LAW 1673) · 20+ YEARS EXPERIENCE · NATIONWIDE COVERAGE

Certified Valuation & Appraisal Services in Colombia

Dual-compliant USPAP, IVS, IFRS 13 / IAS 16, US GAAP ASC 820, and Colombian Law 1673 & Resolution IGAC 941 of 2026 certified appraisals. Accepted by global banks, Big Four audit firms, and arbitration courts, backed by more than 20 years of pericial history across Bogotá, Medellín, Cali, and nationwide.

Class-A corporate towers, Free Trade Zone industrial plants, fixed asset tagging (IAS 16 / IFRS 13), Oil & Gas infrastructure, biological assets, and dual-certified USPAP/IFRS reports for international syndications and Big Four audits.

20+ Years
Appraisal Leadership
13 Categories
RAA Accreditation
100% Bankable
Global Lenders & Leasing
32 Departments
Colombia-Wide Reach
Proven Appraisal Authority in Colombia · Since 2006 (20+ Years)

Leading Multinationals, Financial Institutions & Government Agencies Trust Our Appraisals

For over 20 years, Goods & Services Consulting S.A.S. has delivered institutional-grade valuation and fixed asset inventory reports for Colombia's most critical public entities and global corporations, including Empresa de Acueducto y Alcantarillado de Bogotá (EAAB), Grupo Energía Bogotá (GEB), Sociedad de Activos Especiales (SAE), Agencia Nacional de Infraestructura (ANI), INDUMIL, OPAIN S.A. (El Dorado International Airport), TransMilenio S.A., SATENA, IGAC, DANE, and multinational leaders like Perficient and GateGroup.

Empresa de Acueducto y Alcantarillado de Bogotá (EAAB)
Grupo Energía Bogotá (GEB)
Secretaría Distrital de Gobierno de Bogotá
Sociedad de Activos Especiales (SAE)
Servicio Geológico Colombiano (SGC)
Superintendencia del Subsidio Familiar (Supersubsidio)
Agencia de Desarrollo Rural (ADR)
GateGroup Colombia
Agencia Nacional de Infraestructura (ANI)
OPAIN S.A. - Aeropuerto Internacional El Dorado
SUDECO Agencia de Aduanas
Perficient Colombia
INDUMIL - Industria Militar de Colombia
SATENA - Servicio Aéreo a Territorios Nacionales
IGAC - Instituto Geográfico Agustín Codazzi
DANE - Departamento Administrativo Nacional de Estadística
Universidad del Tolima
TransMilenio S.A.
Acueducto Metropolitano de Bucaramanga (AMB)

20+ Years of Pericial Leadership

Founded in 2006, delivering institutional valuation with physical offices in Bogotá D.C., Medellín, and Cali, providing immediate technical inspection nationwide across Colombia's 32 departments.

RAA Accredited Appraisers (Law 1673)

Certified under Colombian Law 1673 of 2013 across all 13 official RAA categories, operating in full compliance with Decree 556 and the latest statutory provisions of IGAC Resolution 941 of 2026.

IVS, IFRS & USPAP Standards

Active Appraisal Institute (U.S.) designated experts delivering bilingual English/Spanish reports structured for IFRS 13 Fair Value, US GAAP ASC 820, and Big Four audit review (PwC, EY, Deloitte, KPMG).

100% Bankable & Insurable Worldwide

Unreserved acceptance by tier-one domestic banks (ASOBANCARIA), multilateral credit syndicates, leading global reinsurers (Lloyd's, Swiss Re), and Colombian commercial courts under CGP Art. 226.

Do you require an institutional valuation or appraisal in Colombia?

Submit your asset details for immediate confidential consultation via WhatsApp with a certified RAA valuation partner at our national desk.

Direct partner desk · Bilingual practice (English / Spanish) · National desk: +57 (317) 639 4990 · Email: licitaciones@goodsyservices.com

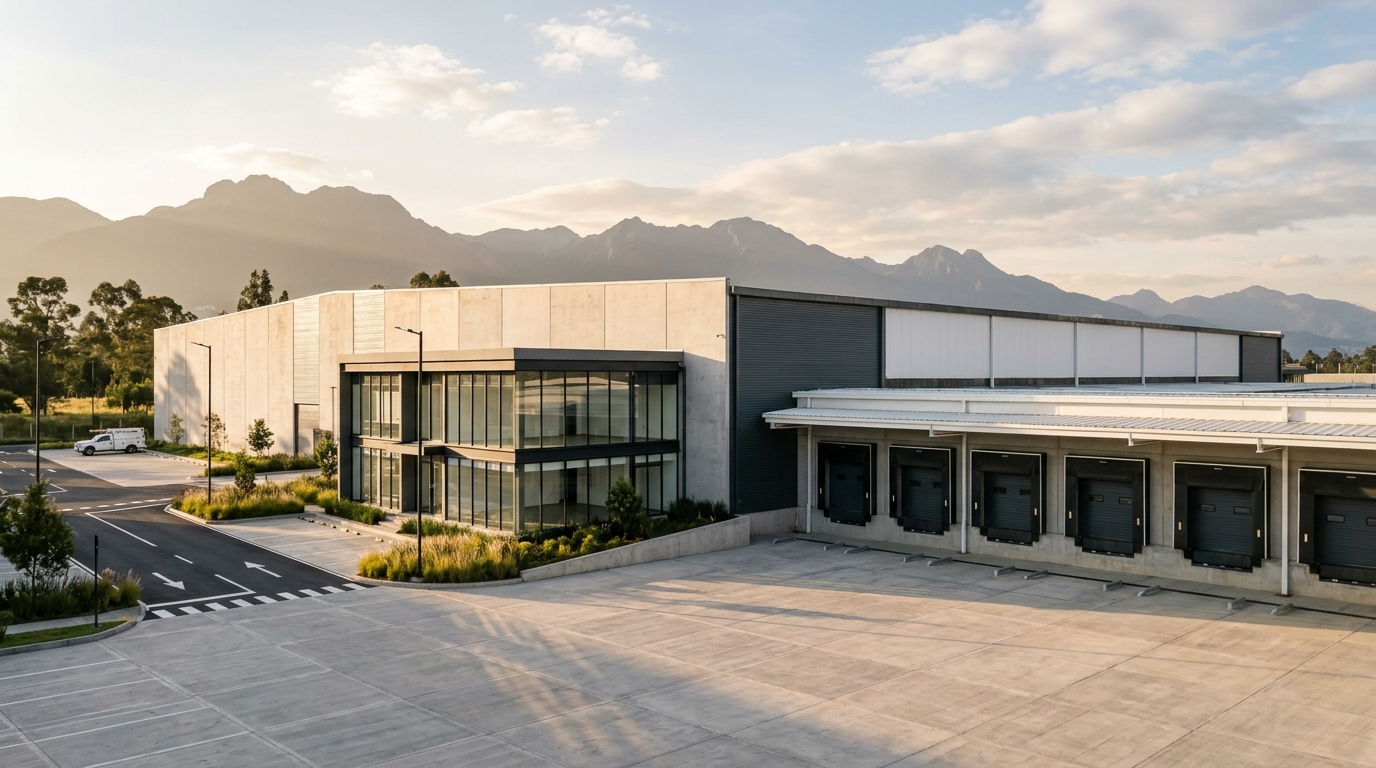
/// RAA CATEGORIES 1 & 6 · COMMERCIAL, OFFICE & LOGISTICS REAL ESTATE

Commercial, Office, Industrial & Prime Real Estate Appraisals

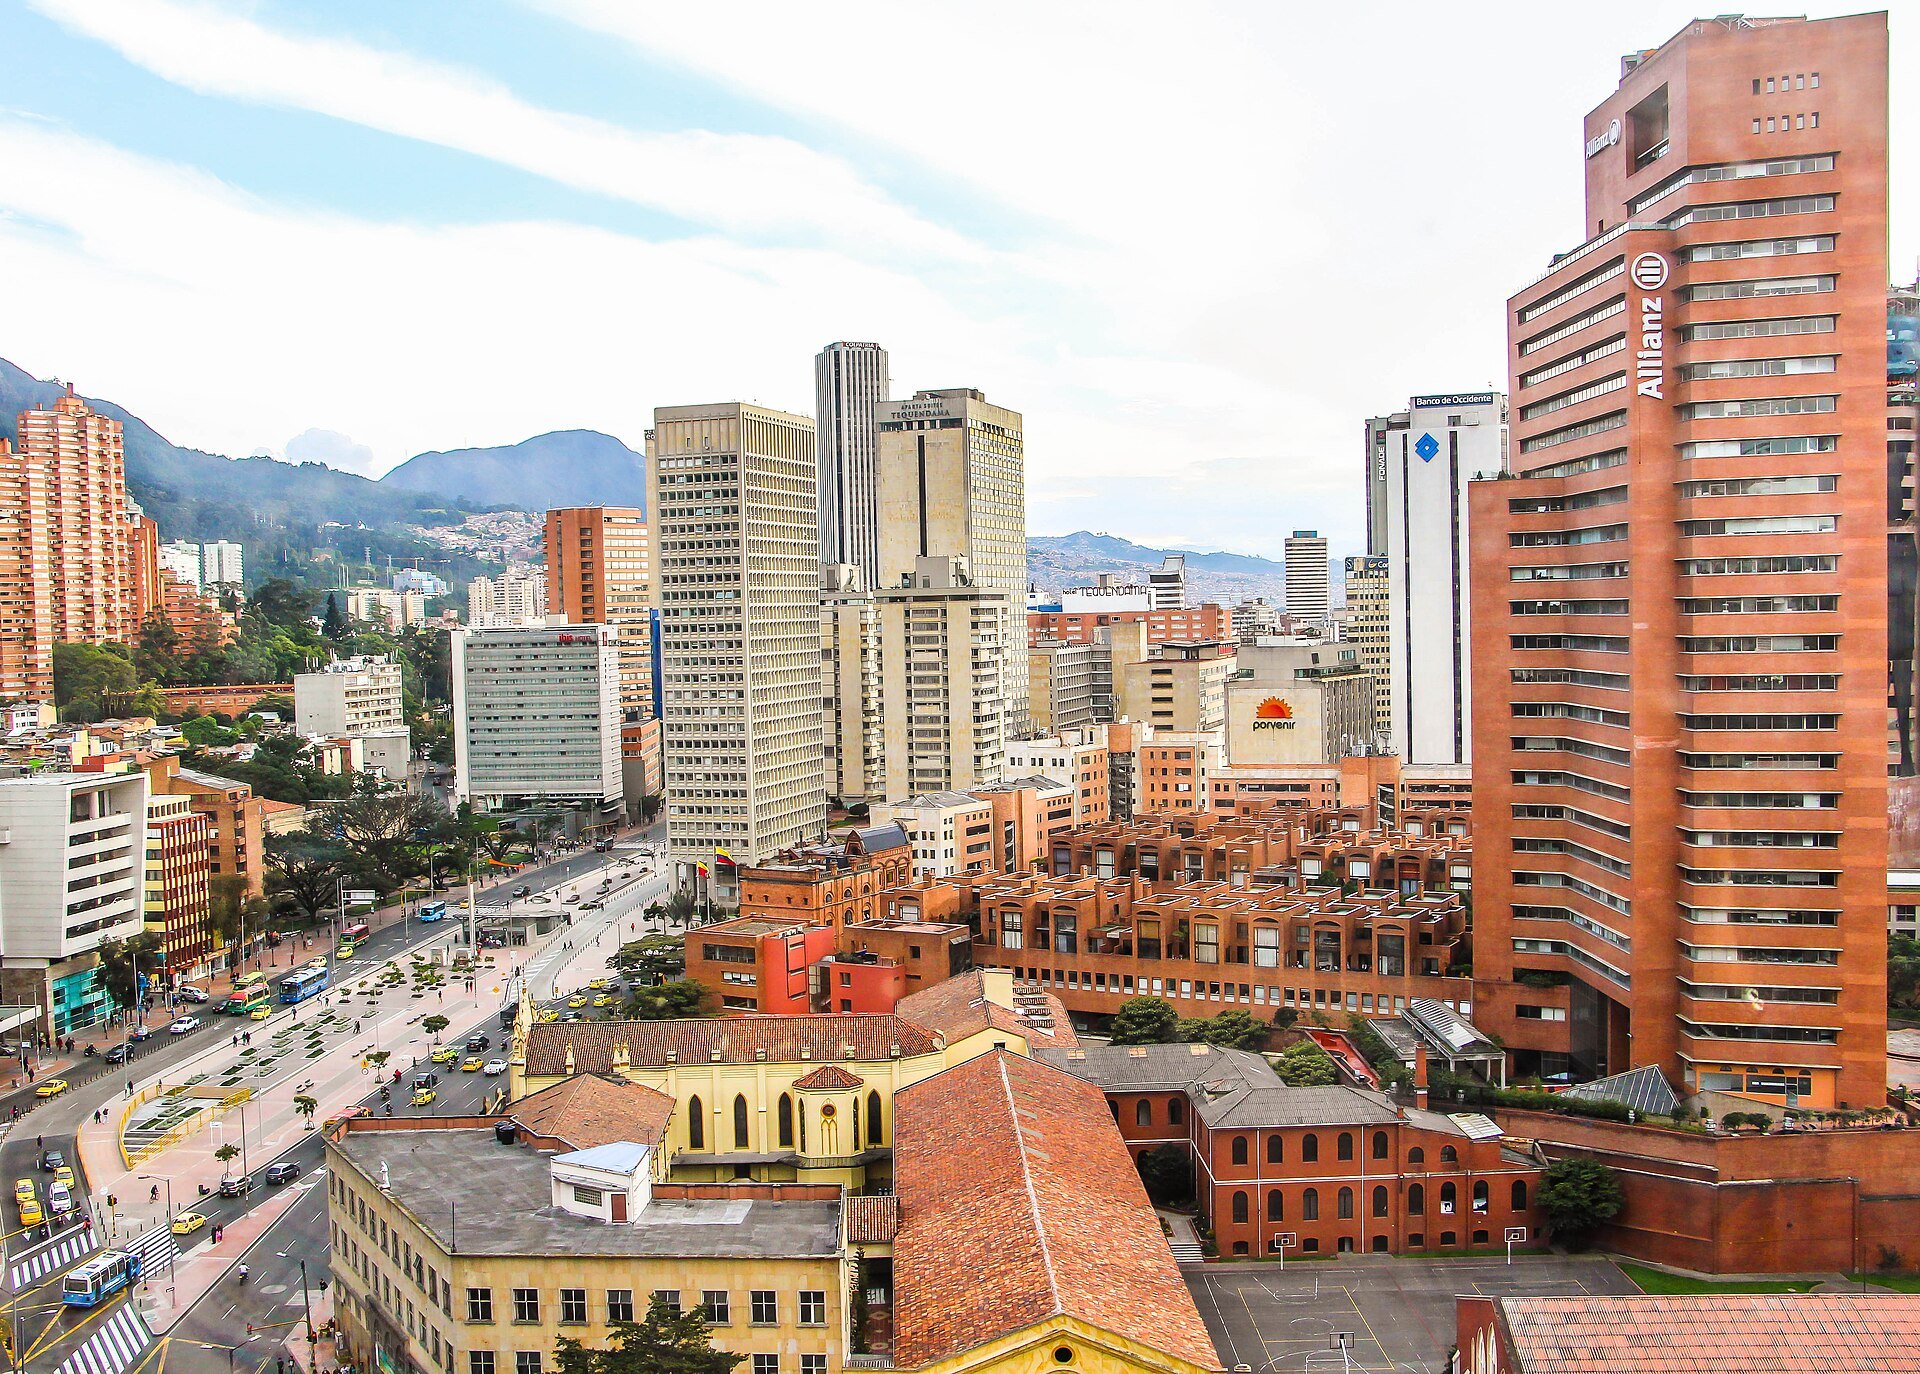
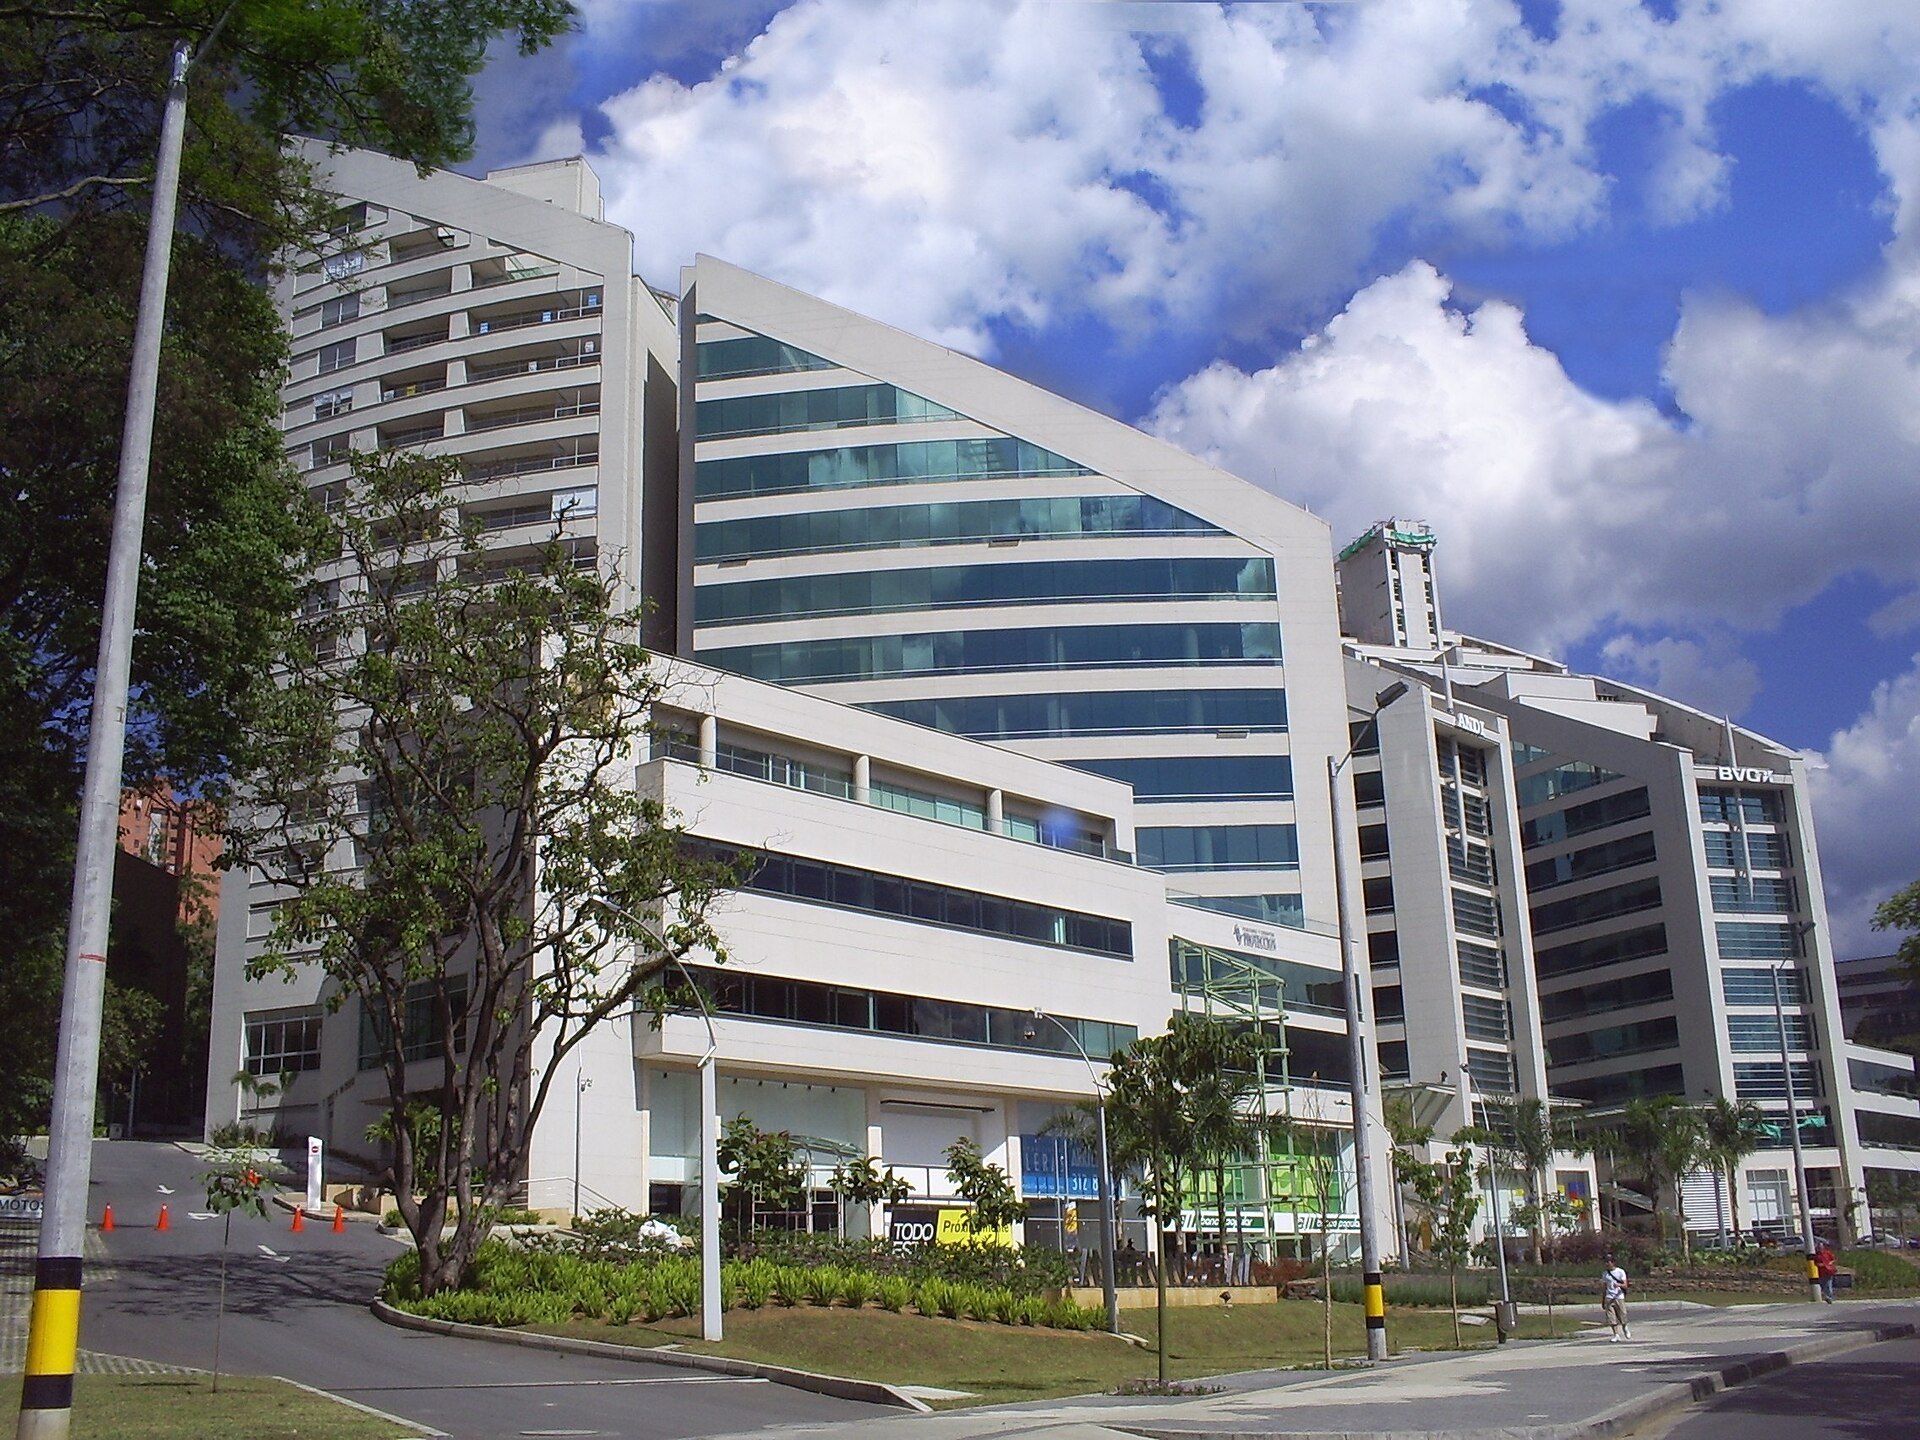
Institutional valuation of commercial real estate across Colombia demands rigorous multi-approach econometric modeling. Whether underwriting Class-A corporate towers along Bogotá's Calle 72 and Chicó, luxury shopping centers in Medellín's Milla de Oro, or modern logistics distribution centers in the Free Trade Zones of the Caribbean, our reports satisfy both Colombian statutory law (IGAC Resolution 941 of 2026) and international institutional standards (IVS 400 and USPAP).

We execute dual valuation methodologies: The Sales Comparison Approach utilizing hedonic regression matrices that adjust for floor plate usable efficiency (BOMA standards), parking allocation ratios, building vintage, and LEED sustainability certifications; and The Income Capitalization Approach executing both Direct Capitalization and 10-year Discounted Cash Flow (DCF) models based on audited tenant rollover schedules, vacancy reserves, and market capitalization rates (Cap Rates).

Institutional Certainty for Credit Committees & Investment Funds: Rigorous hedonic regression matrices and 10-year Discounted Cash Flow (DCF) models reconcile certified appraisals with BOMA floor plate efficiency, tenant lease covenants (IPC indexations), and municipal POT zoning certificates.
  • Class-A & Prime Corporate Offices: Financial district towers in Bogotá (Chicó, Calle 72, Salitre), Medellín (El Poblado), and Cali.
  • Logistics Hubs & Distribution Centers (CEDI): High-clearance cross-dock facilities across Free Trade Zones and major logistics corridors.
  • Regional Shopping Centers & Retail Strips: Anchor tenant sales ratios, foot-traffic counts, occupancy costs, and triple-net (NNN) lease yields.
  • Industrial Land & Urban Expansion Parcels: Residual land valuation modeling buildable FAR densities and master plan infrastructure costs.
Commercial real estate appraisal in Colombia by Goods & Services Consulting COMMERCIAL REAL ESTATE · CLASS-A & LOGISTICS

Key Pericial Indicators · Commercial Real Estate

7.25% – 9.15%
Prime Cap Rates for Class-A CBD corporate towers (Bogotá Chicó & Medellín Milla de Oro)
12% – 18%
BOMA standard usable vs. gross leasable area (GLA) audited load factors
3 to 5 Days
Turnaround timeframe for certified commercial & office valuation reports
Level 2 / 3
IFRS 13 & US GAAP ASC 820 Fair Value hierarchy classification

Technical Valuation Framework

StandardsIGAC Res. 941/2026 · IVS 400 · USPAP Standards 1 & 2 · IFRS 13
ApproachesSales Comparison (Homogenization Matrix) · Income Capitalization (DCF) · Cost Approach
DeliverablesCertified RAA Appraisal Report · Non-redacted Financial Excel Model · POT Zoning Certificate
100% Bankable · USPAP & IFRS 13 Compliant
/// RAA CATEGORY 7 · INDUSTRIAL MACHINERY, PLANTS & HEAVY EQUIPMENT

Industrial Machinery, Production Lines & Heavy Equipment

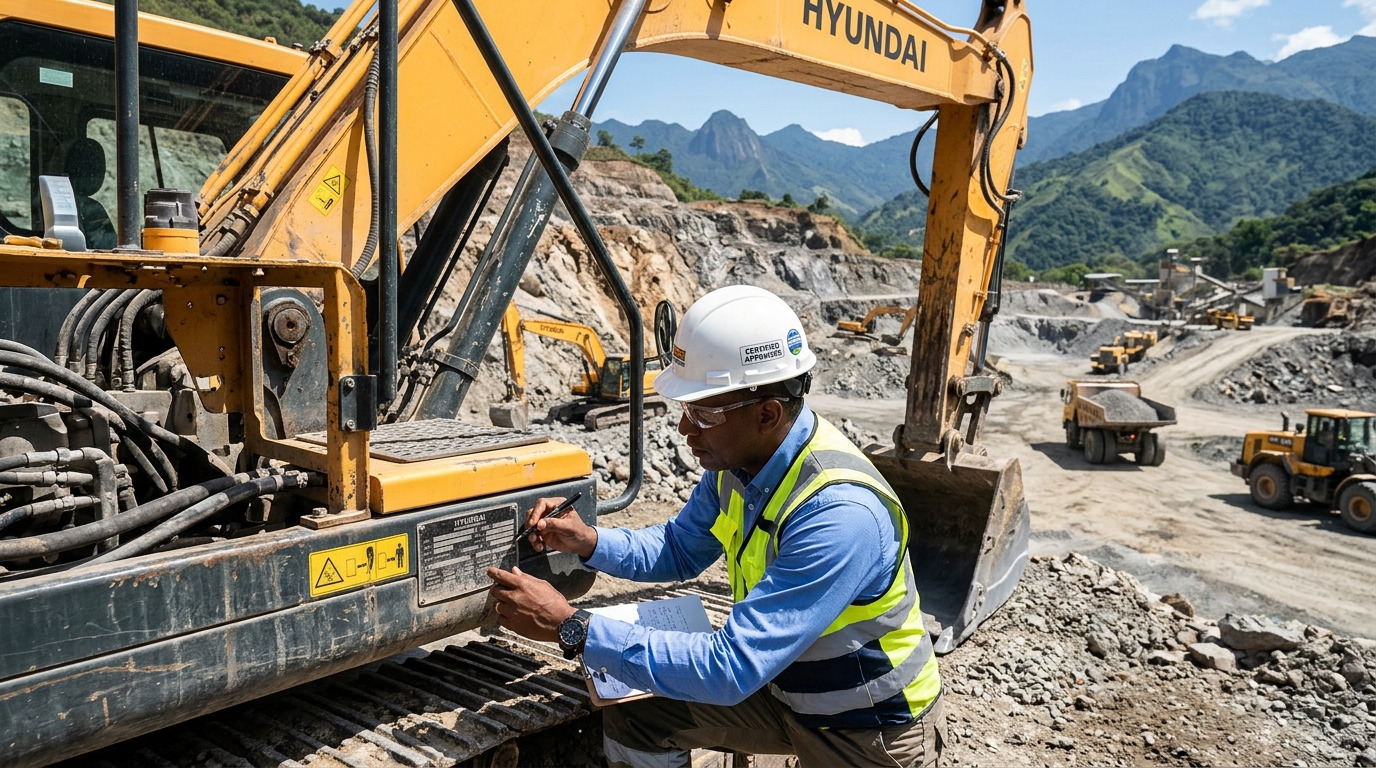
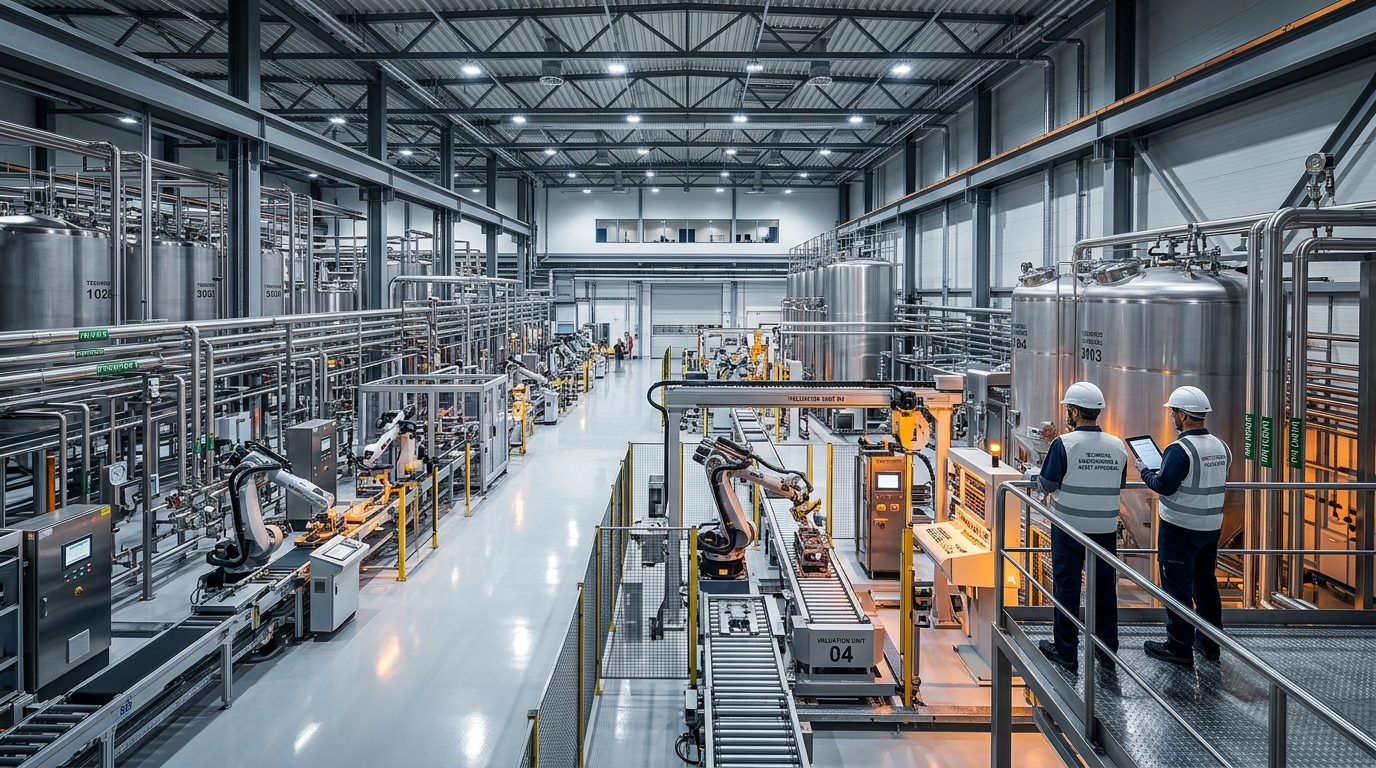
Valuing industrial machinery and manufacturing plant assets in Colombia requires engineering precision combined with deep macroeconomic awareness. Our engineering partners conduct comprehensive plant inspections under IVS 300 (Plant and Equipment), applying Depreciated Replacement Cost (DRC) calibrated with the Ross-Heidecke depreciation methodology, which simultaneously assesses physical deterioration and functional obsolescence.

We trace every asset against its original equipment manufacturer (OEM) procurement documentation, customs declarations (Declaraciones de Importación DIAN), and capital upgrade logbooks. Our reports establish unassailable valuations for Fair Market Value in Continued Use, Orderly Liquidation Value (OLV), and Forced Liquidation Value (FLV), serving credit syndications, corporate restructuring, insurance scheduling, and cross-border M&A due diligence.

Audit-Proof Industrial Balance Sheet Valuation: Engineering appraisers cross-reference OEM replacement cost quotes, import tariff structures (aranceles), installation costs, and functional/economic obsolescence to determine true Fair Value under IVS 300 and IAS 16.
  • Manufacturing & Assembly Lines: Automotive, pharmaceutical, metalworking, plastics, and food processing lines.
  • Civil Construction & Mining Fleets: Heavy yellow machinery, excavators, tunnel boring machines, and mobile batching plants.
  • Power Generation & Transformers: Hydroelectric turbines, thermal generation units, co-generation plants, and high-voltage substations.
  • Specialized Balance Sheet Portfolios: Componentized plant appraisals with technical plate matching and DIAN import declaration audits.
Industrial machinery and heavy equipment appraisal in Colombia HEAVY MACHINERY · INDUSTRIAL PLANTS · IVS 300

Key Pericial Indicators · Plant & Machinery

Ross-Heidecke
Depreciation model calibrating physical wear, maintenance history & age-to-life ratios
FLV & OLV
Forced Liquidation & Orderly Liquidation Values modeled for banking collateral
100% Tax Deductible
Audited remaining useful life (RUL) schedules accepted by DIAN and external auditors
3 to 7 Days
Certified engineering inspection & bilingual appraisal dossier delivery nationwide

Technical Valuation Framework

StandardsIVS 300 (Plant and Equipment) · IAS 16 · ASME Codes · RAA Category 7
MethodologyDepreciated Replacement Cost (DRC) · OEM Replacement Indexing · Secondary Market Data
ScopeComponentized technical asset register, serial matching & functional obsolescence analysis
100% Audit-Proof · Ross-Heidecke Engineering Depreciations
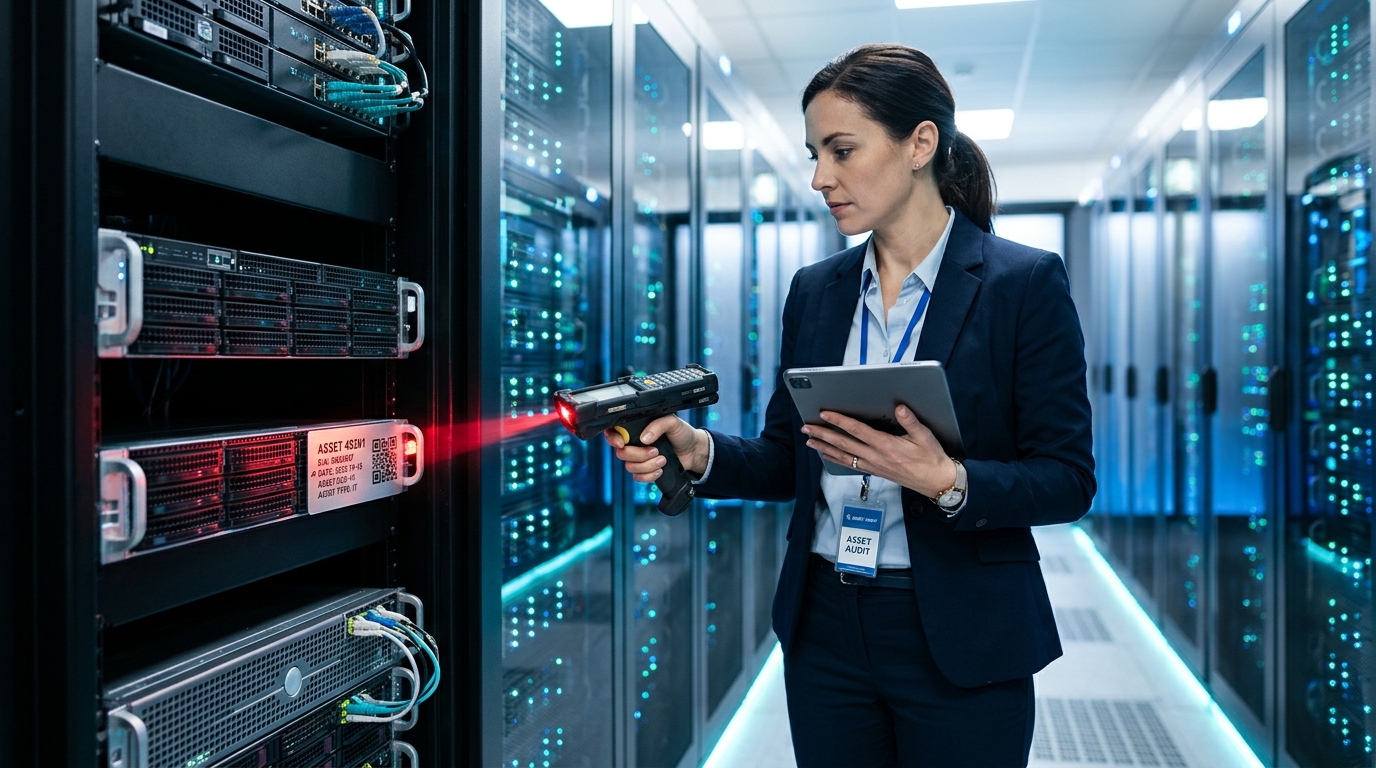
/// RAA CATEGORY 7 · IFRS FIXED ASSET INVENTORY & ERP RECONCILIATION

Physical Asset Inventory, Barcode/RFID Tagging & ERP IFRS Reconciliation

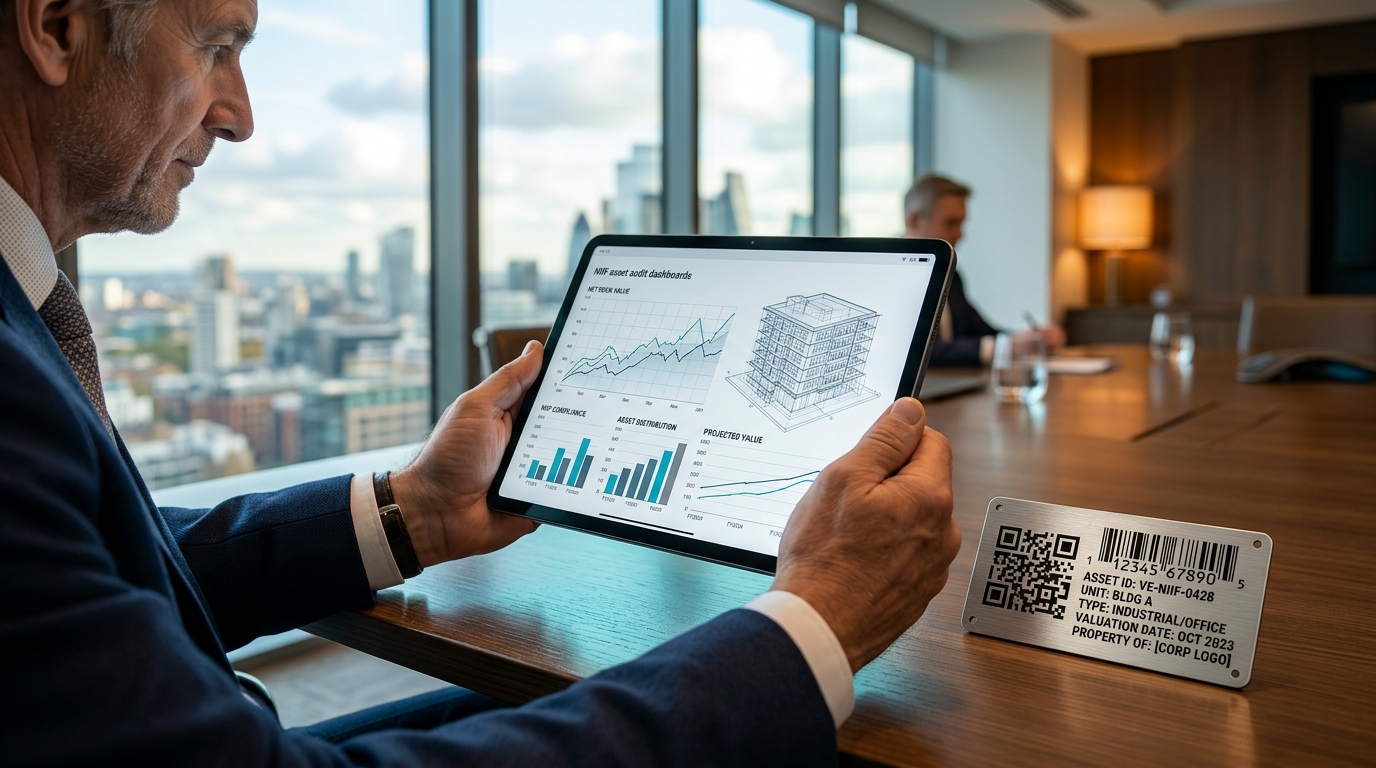
Corporate financial statements frequently suffer from severe discrepancies between general ledger accounting records and physical asset reality. Goods & Services Consulting deploys nationwide field engineering teams to execute wall-to-wall physical inventories, tagging each fixed asset with high-durability anodized aluminum barcode plates, chemical-resistant QR labels, or passive UHF RFID tags designed for harsh industrial environments.

Following field data capture, our senior forensic accountants execute bilateral reconciliation with corporate ERP systems (including SAP S/4HANA, Oracle Cloud ERP, Microsoft Dynamics 365, and Infor). We componentize complex assets under IAS 16 Property, Plant and Equipment, identify unrecorded asset retirements (bajas de activos), re-estimate remaining useful lives, and establish auditable baseline values for annual impairment testing under IAS 36.

Eliminating Ghost Assets & Balancing Books: Physical wall-to-wall inspections resolve discrepancies between operational realities and accounting balances, identifying phantom assets (bajas de activos) and capitalizing unrecorded enhancements under IAS 16.
  • Wall-to-Wall Physical Tagging: Specialized field teams deployed to factories, offices, clinics, and multi-site store chains.
  • Rugged Anodized Barcode Plates: High-durability metal and thermal barcode/QR tags resistant to chemical cleaning, heat, and outdoor weathering.
  • ERP Ledger Reconciliation: Clean bilateral matching to SAP S/4HANA, Oracle Cloud ERP, Microsoft Dynamics 365, and local software.
  • Impairment Testing Support (IAS 36): Technical testing of Cash Generating Units (CGUs) to determine recoverable amounts vs carrying values.
Fixed asset physical inventory and barcode tagging in Colombia ERP RECONCILIATION · SAP · ORACLE · DYNAMICS

Key Pericial Indicators · Fixed Asset Management

99.8% Accuracy
Audit reconciliation rate between physical floor counts and accounting ledgers
IAS 16 Componentization
Breakdown of complex multi-part assets into distinct depreciation schedules
Barcode / RFID
Industrial anodized aluminum barcodes, rugged QR codes & UHF RFID tags
Big Four Ready
Zero audit observations in external reviews by Deloitte, PwC, EY & KPMG

Technical Valuation Framework

StandardsIAS 16 (PP&E) · IAS 36 (Impairment) · IFRS 13 · Law 1314/2009
TechnologyIndustrial Mobile Scanners · UHF RFID Readers · Cloud Master Databases
DeliverablesERP-ready Upload CSV/Excel · Discrepancy Matrix · Accounting Policy Manual
Wall-to-Wall Reconciliation · Audit-Ready Upload Files
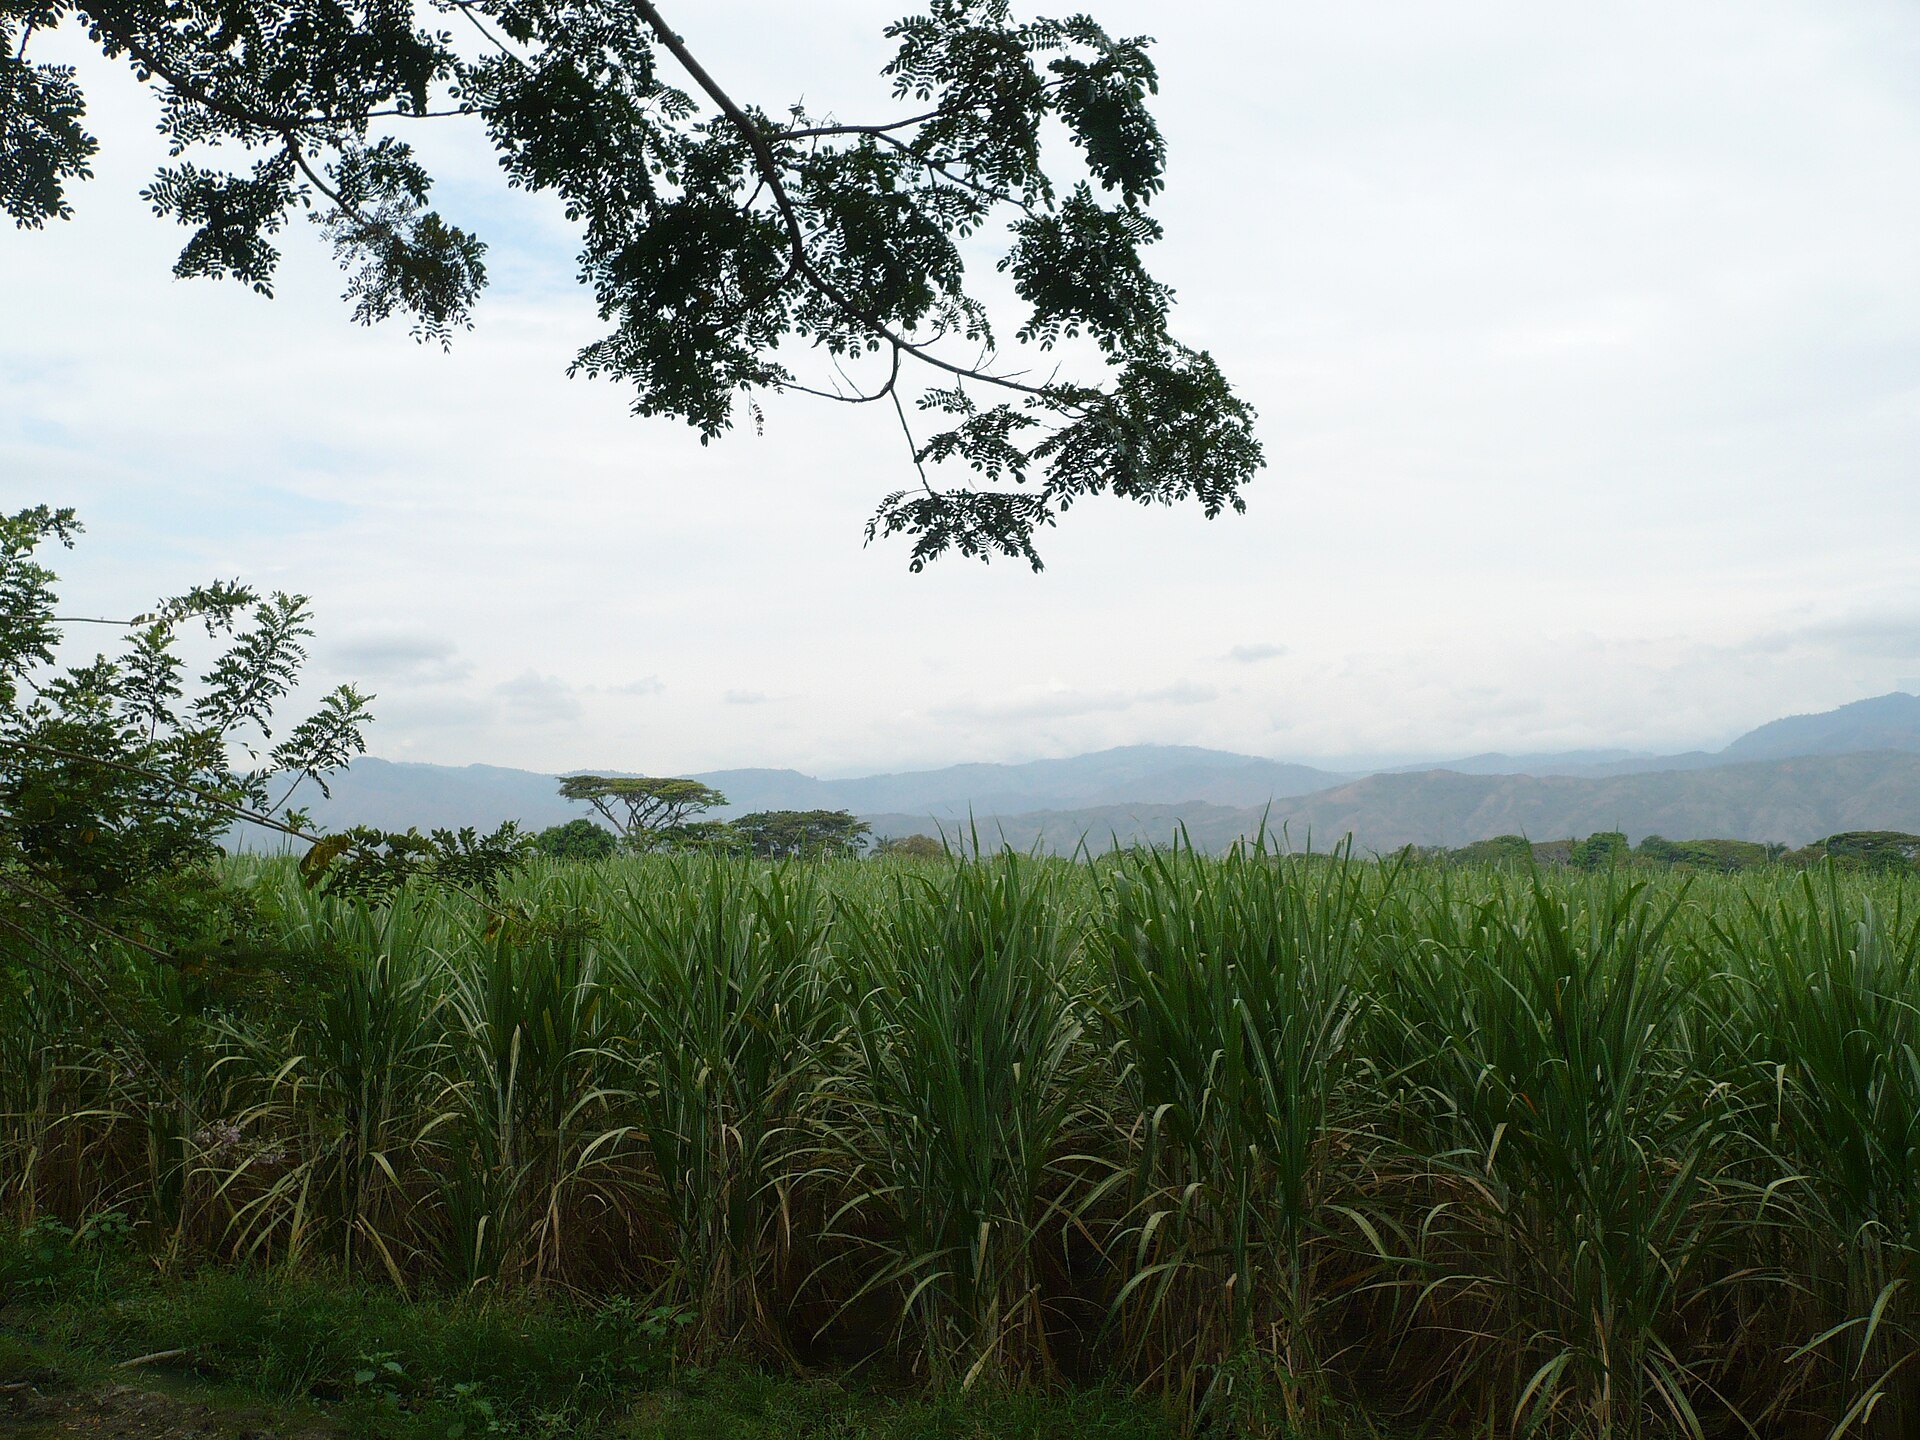
/// RAA CATEGORIES 2 & 12 · AGRIBUSINESS, AGRO-INDUSTRIAL & BIOLOGICAL ASSETS

Agribusiness, Agro-industrial Facilities & Biological Assets (IAS 41)

Colombia's agricultural frontiers—from the vast sugarcane plantations of the Valle del Cauca to the intensive oil palm plantations of the Eastern Plains (Llanos Orientales), commercial forestry developments in Antioquia, and highland avocado/coffee estates—require specialized multidisciplinary valuation. We integrate certified agronomists, civil hydrologists, and industrial economists to deliver rigorous valuations under IAS 41 (Agriculture) and IAS 16 (Bearer Plants).

We model both the biological assets (standing crops, livestock, bearer fruit trees, commercial timber inventories) and the agro-industrial processing infrastructure (sugar mills, extraction plants, irrigation networks, climate-controlled packing houses, and deep well concessions). Our agronomic models account for soil classification classes (IGAC Agrological Capacity), water concession rights (concesiones de agua CAR), climatic risk factors, and international commodity price cycles (FOB Buenaventura/Cartagena).

Bridging Biological Cycles with Industrial Agro-Processing: Our agricultural engineers and industrial economists value both the biological assets under IAS 41 (standing sugarcane, oil palm, timber, coffee) and the heavy processing infrastructure under IAS 16 (mills, extraction plants, irrigation networks).
  • Sugarcane & Palm Oil Mills (Ingenios y Extractoras): Multi-megawatt co-generation boilers, crushing tandems, refining units, and storage silos.
  • Biological Bearer Plants (Plantas Productoras): Productive fruit orchards, rubber plantations, oil palm acreage, and commercial forestry.
  • Irrigation Networks & Water Infrastructure: Deep well concessions, automated pivot systems, reservoirs, and drainage canals.
  • Livestock & Breeding Stocks: Genetic breeding herds, poultry houses, feedlots, and aquaculture farming facilities.
Agribusiness, sugar mills and biological asset valuation in Colombia IAS 41 AGRICULTURE · SUGAR MILLS · PALM OIL

Key Pericial Indicators · Agribusiness & Bio-Assets

IAS 41 Fair Value
Biological asset biological cycle valuation less estimated point-of-sale costs
12 to 25 Years
Bearer plant productive economic lifecycle modeled for palm, citrus & forestry
Water & Environmental
Valuation of legal water concessions (concesiones de agua) and CAR permits
5 to 10 Days
Turnaround for comprehensive agro-industrial plant & hacienda appraisals

Technical Valuation Framework

StandardsIAS 41 (Agriculture) · IAS 16 (Bearer Plants) · RAA Categories 2 & 12
MethodologiesNet Realizable Value · Multi-period DCF · Agroclimatic Soil Homogenization
DeliverablesAgronomic Pericial Dossier · GIS Cadastral Polygon · Bio-Asset Fair Value Ledger
IAS 41 & IAS 16 Compliant · Multi-Period DCF Harvest Models
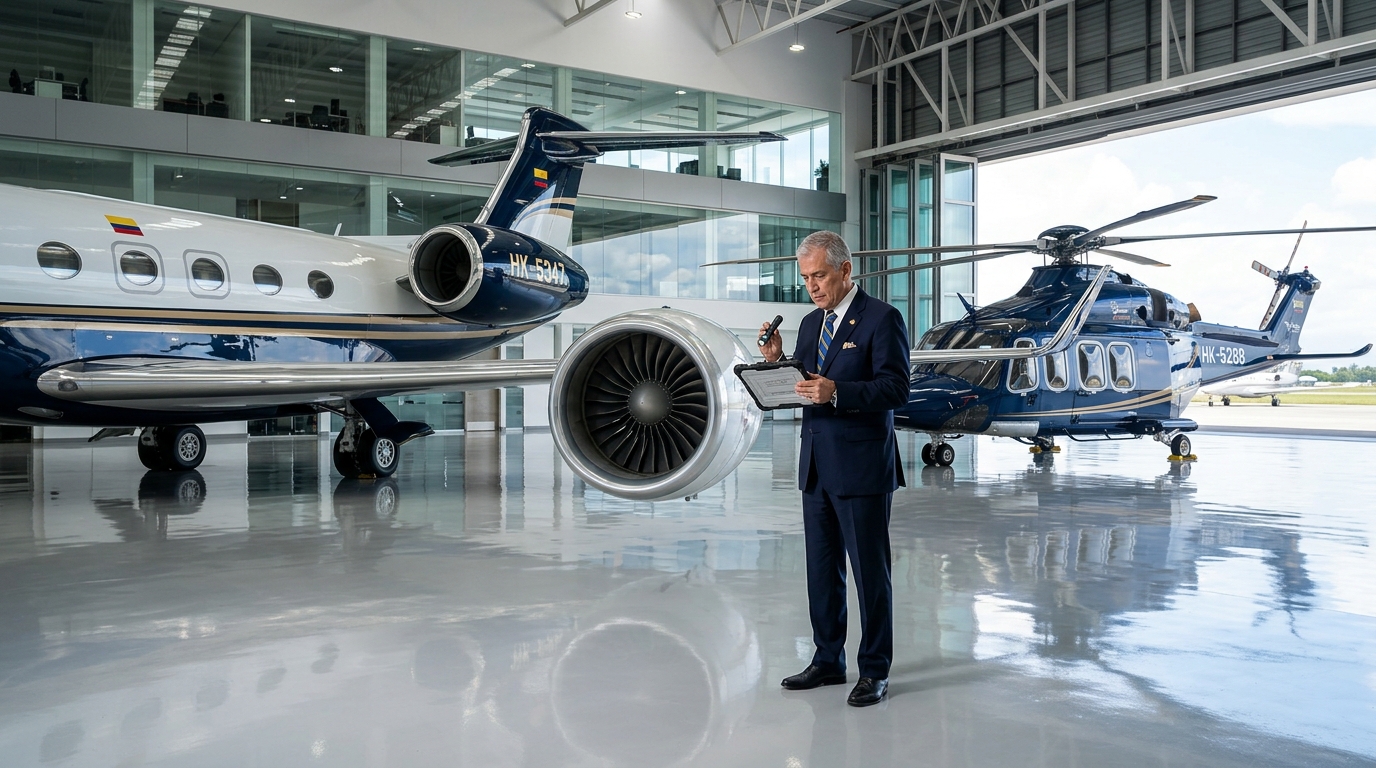
/// RAA CATEGORIES 3 & 4 · CORPORATE FLEETS, AIRCRAFT & MARINE VESSELS

Corporate Fleets, Executive Aircraft & Marine Vessels

Valuing high-capital transportation assets demands global aerospace and maritime pericial credentials. Goods & Services Consulting provides certified appraisal services for executive corporate jets, commercial turboprops, offshore transport helicopters, and riverine/ocean-going marine vessels operating within Colombia and international jurisdictions.

Our aviation appraisals comply with Colombian Civil Aviation Regulations (Aerocivil RAC), FAA guidelines, and international market databases (AMSTAT, Vref, and HeliValue$). We conduct rigorous technical audits of airframe total time, engine cycles since major overhaul (SMOH), hot section inspections, life-limited parts (LLP) status, avionics suites (NextGen / ADS-B Out compliance), and historical damage records. For maritime assets, we inspect hull integrity, propulsion systems, and compliance with DIMAR regulations.

Global Aerospace & Maritime Pericial Expertise: Executive jets, commercial turboprops, offshore transport helicopters, and riverine/maritime cargo fleets require meticulous maintenance logbook auditing, engine cycle tracking, avionics checks, and structural corrosion inspections.
  • Executive Jets & Turboprops: Gulfstream, Bombardier Challenger/Global, Dassault Falcon, Beechcraft King Air, and Cessna Citation.
  • Commercial & Offshore Helicopters: Bell, Airbus Helicopters, and Leonardo fleets configured for executive, medical, and O&G transport.
  • Marine Cargo & Support Vessels: Tugs, ocean-going barges, offshore supply vessels (OSVs), and specialized dredge carriers.
  • Corporate Truck & Utility Fleets: Telematics-audited distribution fleets, heavy haulers, and refrigerated transport trailers.
Executive aircraft, corporate fleets and marine valuation in Colombia AEROSPACE · OFFSHORE · LOGISTICS FLEETS

Key Pericial Indicators · Aviation & Marine Fleets

Airframe & Engine Logs
Hours/cycles tracking against FAA/EASA airworthiness directives and TBO limits
DIMAR Standards
Marine hull and propulsion machinery valuation for tugs, barges & supply vessels
Vref / AMSTAT
Global market pricing data indexed to Colombian customs import baselines
3 to 5 Days
Bilingual appraisal reports formatted for cross-border aviation leasing & insurance

Technical Valuation Framework

StandardsAerocivil RAC · FAA Standards · IVS 300 · DIMAR Regulations
DatabasesAMSTAT Worldwide · Vref Aviation Index · HeliValue$ BlueBook
DeliverablesCertified Airworthiness Valuation Dossier · Engine Maintenance Reserve Schedule
Aerocivil RAC, FAA & DIMAR Standards · BlueBook Indexed
/// RAA CATEGORY 7 · OIL & GAS, MINING & PETROCHEMICAL (API 650)

Oil & Gas, Mining & Petrochemical Upstream/Midstream (API 650)

Valuing oil and gas extraction facilities, petrochemical processing plants, refining assets, and energy infrastructure requires deep familiarity with technical engineering codes and industry-specific accounting standards. Our senior petroleum and mechanical engineers inspect surface facilities, pipeline pump stations, and storage tank batteries in strict accordance with API 650 (Welded Steel Tanks for Oil Storage), API 653, and ASME Boiler and Pressure Vessel Codes.

We execute detailed bottom-up cost modeling that captures replacement cost new, functional obsolescence driven by field depletion or sulfur content, and economic obsolescence tied to global Brent crude volatility and regulatory shifts. Furthermore, our valuations incorporate Asset Retirement Obligations (ARO) under IAS 37, delivering defensible asset baselines for international joint venture audits, farm-in/farm-out transactions, and institutional collateral packages.

Heavy Petrochemical & Mining Valuation Architecture: Certified petroleum and mechanical engineers assess surface processing facilities, pumping stations, crude pipelines, and storage terminals, adjusting for metallurgical corrosion, sulfur embrittlement, throughput utilization, and field depletion curves.
  • Crude & Refined Product Storage Terminals: API 650 tank farms, manifold systems, vapor recovery units, and marine loading arms.
  • Upstream Wellhead Gathering & Separation Stations: Multi-phase test separators, crude stabilization units, and water injection pumps.
  • Gas Processing & Cryogenic Fractionation Plants: Amine sweetening trains, molecular sieve dehydrators, and turbo-expanders.
  • Mining Beneficiation & Conveyance Plants: Primary gyratory crushers, SAG/ball mills, flotation cells, and tailing dam monitoring facilities.
Oil and gas surface infrastructure and petrochemical appraisal in Colombia UPSTREAM & MIDSTREAM · API 650 · REFINERIES

Key Pericial Indicators · Oil & Gas / Energy

API 650 / 653
Structural tank shell thickness, floor corrosion & settlement pericial audit
ASME Section VIII
Pressure vessels, separators, heat exchangers & dehydration train assessment
IAS 37 ARO Provision
Asset Retirement Obligation & environmental remediation liability modeling
100% SEC Compliant
Auditable Level 3 Fair Value schedules for reserve disclosures and JV reporting

Technical Valuation Framework

StandardsAPI 650 / 653 · ASME Boiler Codes · IVS 300 · IAS 37 (ARO)
InspectionUltrasonic Thickness Testing (UT) · Metallurgical Fatigue & Corrosion Audits
DeliverablesCertified RAA Category 13 Report · Remaining Useful Life (RUL) Modeling
API 650 & ASME Code Engineering · IAS 37 Decommissioning Reserves
/// RAA CATEGORIES 1, 6 & 7 · BANK COLLATERAL & SYNDICATED LEASING

Collateral Valuation for Banking Syndications & Leasing

Securing multi-million dollar corporate debt facilities, structured project finance, or cross-border equipment leasing requires valuation reports that strictly align with both local regulatory directives (Superintendencia Financiera de Colombia Circular Básica Jurídica) and international credit risk underwriting frameworks. We provide authoritative collateral underwriting for domestic banks (Bancolombia, Banco de Bogotá, Davivienda, BBVA) and multilateral development financiers (IFC, IDB Invest, CAF).

Our pericial appraisals establish dual value conclusions: Market Value for balance sheet solvency and loan covenant testing, and Orderly Liquidation Value (OLV) / Forced Liquidation Value (FLV) to model downside recovery under expedited workout horizons. Every collateral dossier includes legal title chain verification, encumbrance checks (gravámenes y limitaciones al dominio), and liquidity absorption analyses.

Unlocking Bank Credit & Protecting Balance Sheets: Approved by all major Colombian financial institutions (Bancolombia, Banco de Bogotá, Davivienda, BBVA, Itaú) and international development banks (IFC, IDB Invest, CAF) for syndicated loans, real estate guarantees, and equipment lease lines.
  • Syndicated Loan Collateral Packages: Multi-asset pledges uniting real estate, industrial equipment, and enterprise shares.
  • Sale & Leaseback Structuring: Unlocking capital from corporate headquarters and operational real estate portfolios.
  • Commercial Equipment Leasing Lines: Accurate residual value forecasts at lease maturity under US GAAP / IFRS 16.
  • Distressed Asset & Debt Workout Valuations: Insolvency guarantees under Law 1116 corporate restructuring processes.
Banking collateral and syndicated credit facility valuation in Colombia BANK COLLATERAL · SYNDICATED LOANS · LEASING

Key Pericial Indicators · Bank Collateral & Credit

LTV Optimization
Loan-to-Value ratios calculated under both Market Value and Liquidation Value
Superfinanciera Approved
Full adherence to credit collateral guidelines for Colombian financial entities
Quick Liquidation Curve
Discounted cash recovery modeling under 90-day, 180-day, and 360-day scenarios
2 to 4 Days
Expedited underwriting turnaround for tier-one corporate financing deals

Technical Valuation Framework

RegulatorsSuperintendencia Financiera de Colombia · ASOBANCARIA Standards · IVS 104
PremisesFair Market Value · Orderly Liquidation Value (OLV) · Forced Liquidation (FLV)
DeliverablesBank-Formatted Appraisal Certificate · Legal Title Study Audit · Liquidity Risk Rating
100% Accepted by ASOBANCARIA & Multilateral Development Banks
/// RAA REGISTERED EXPERT WITNESS · JUDICIAL LITIGATION & ARBITRATION

Expert Witness Reports for Commercial Litigation & Arbitration

In high-stakes commercial litigation, shareholder oppression disputes, expropriation indemnification proceedings, and international commercial arbitration, the outcome routinely hinges upon the technical rigor and procedural admissibility of the expert appraisal. Goods & Services Consulting prepares judicial expert witness reports in strict compliance with Article 226 of the Colombian General Code of Process (Código General del Proceso - Ley 1564 de 2012).

Our senior partners possess decades of courtroom experience defending valuation methodologies under rigorous cross-examination before circuit civil courts, administrative tribunals, and leading arbitration centers—including the Centro de Arbitraje de la Cámara de Comercio de Bogotá (CCB), Medellín (CCMA), Cali (CCC), and international forums under ICC (Paris) and UNCITRAL rules. We quantify direct damages (daño emergente) and lost future profits (lucro cesante) with unassailable econometric precision.

Forensic Pericial Defense in High-Stakes Legal Disputes: In commercial litigation, shareholder buyouts, expropriation disputes (expropiación judicial o administrativa), and international arbitrations, an unassailable expert witness report with rigorous econometric proof makes the difference between winning and losing millions in court.
  • Commercial Court & Arbitration Proceedings: Chamber of Commerce arbitration centers (Bogotá CCB, Medellín CCMA, Cali CCC, and ICC Paris).
  • Infrastructure Expropriation Defense: Counter-appraisals challenging IDU, Metro de Bogotá, ANI, and municipal road widening indemnifications.
  • Shareholder & Partnership Dissolutions: Equitable partition of corporate equity, commercial premises, and operational assets.
  • Estate Partitions & Divorce Settlements: Impartial, legally binding appraisals for family notarías and circuit civil courts.
Judicial appraisal and expert witness dictamen pericial under CGP 226 in Colombia EXPERT WITNESS · LITIGATION · ARBITRATION

Key Pericial Indicators · Litigation & Arbitration

CGP Art. 226
Full procedural and evidentiary compliance under Colombia's General Code of Process
100% In-Court Defense
Direct pericial oral testimony, cross-examination defense, and clarification hearings
Expropriation Damage
Direct damage (daño emergente) and lost profits (lucro cesante) financial calculations
Bilingual Dossiers
Spanish procedural filings paired with certified English translations for CIADI / ICC

Technical Valuation Framework

StatuteLaw 1564/2012 Art. 226-228 · Law 1673/2013 · RAA Certified Expert Witness
ArbitrationCCB Bogotá · CCMA Medellín · CCC Cali · CIADI / ICC Paris Protocols
DeliverablesExpert Witness Dictamen Pericial · Cross-Examination Defense Brief · Mathematical Evidence Files
CGP Art. 226 Compliant · CCB & CIADI Arbitration Defensible
/// RAA CATEGORIES 1, 6 & 7 · INSURABLE VALUE (RCN) & RISK ASSESSMENT

Insurable Replacement Cost New (RCN) & Catastrophic Risk (NSR-10)

A widespread financial error committed by corporate risk managers and condominium boards in Colombia is insuring physical assets based on historical book value or standard commercial market price. In the event of catastrophic loss (fire, explosion, earthquake, flooding), insurance loss adjusters apply underinsurance penalties (regla proporcional / infraseguro), drastically reducing indemnity payments when the insured declared value falls below the true cost to reconstruct or replace.

Goods & Services Consulting calculates exact Insurable Replacement Cost New (Valor de Reposición a Nuevo - VRN). Our engineering quantity surveyors establish ground-up rebuilding estimates compliant with Colombia's earthquake-resistant construction code (Reglamento Colombiano de Construcción Sismo Resistente NSR-10), including debris removal, demolition costs, professional architectural/engineering fees, import tariffs (CIF / aranceles), and international machinery freight.

Protecting Capital from Underinsurance Traps: Standard balance sheet valuations fail insurance audits because they include non-insurable land and deduct historical depreciation. We calculate true Insurable Replacement Cost New (Valor de Reposición a Nuevo - VRN) so your asset is 100% covered without costly over-insurance or catastrophic coinsurance deductions.
  • Industrial Facility Policies: All-risk property coverage (Todo Riesgo Daño Material) for plants, warehouses, and equipment.
  • Commercial Towers & Co-Ownerships (Ley 675): Comprehensive common area and structural rebuilding estimates for residential/office boards.
  • Business Interruption (Lucro Cesante) Audits: Estimating reconstruction lead times, machinery replacement timelines, and lost margins.
  • Reinsurance Slip Documentation: Detailed asset schedules structured for international underwriters at Lloyd's, Munich Re, and Swiss Re.
Insurable Replacement Cost New and risk assessment in Colombia INSURABLE VALUE · REINSURANCE · NSR-10

Key Pericial Indicators · Insurance & Risk

Zero Coinsurance Penalty
Eliminates underinsurance (infraseguro) deductibles during major loss settlements
Demolition & Debris Removal
Includes site clearing, hazardous material disposal & temporary shoring costs
NSR-10 Code Upgrades
Calculates compliance premiums required by current seismic building codes
Customs & Freight Modeling
Accounts for CIF freight, customs duties & international installation surcharges

Technical Valuation Framework

StandardInsurable Replacement Cost New (RCN / VRN) · NSR-10 Seismic Safety Code
EngineeringBottom-Up Quantity Take-Off (QTO) · OEM Quotations · Freight & Engineering Fees
DeliverablesInsurance Asset Register · Coinsurance Defense Dossier · Reinsurance Slip Annexes
Zero Underinsurance Risk · Lloyd's & Swiss Re Underwriting Approved
/// RAA CADASTRAL SPECIALISTS · PROPERTY TAX & CADASTRAL APPEALS

Property Tax (Impuesto Predial) Review & Cadastral Appeals

The accelerated rollout of Colombia's Catastro Multipropósito (Decree 148 of 2020 and Law 1955) has resulted in unprecedented, erratic surges in official cadastral valuations (avalúos catastrales) across Bogotá (UAECD), Medellín, Cali, and regional municipalities. Corporate property owners, logistics operators, and developers frequently receive property tax bills that overestimate commercial values by 30% to over 60%, creating massive cash drain.

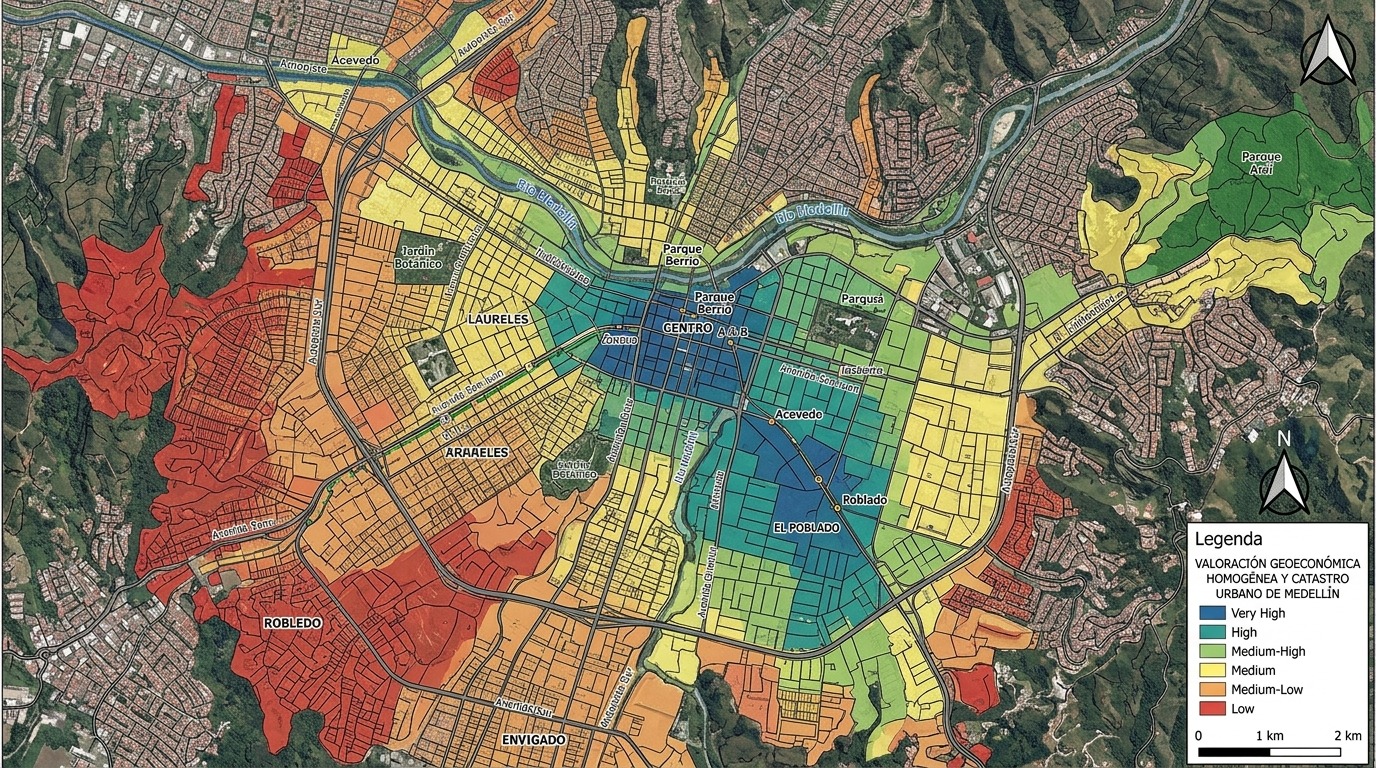
Goods & Services Consulting prepares formal administrative review appeals (reclamaciones de revisión de avalúo catastral) governed by Article 60 of Colombian Law 1673 of 2013 and IGAC Resolution 1040 of 2023. We execute comprehensive technical contra-appraisals (contra-avalúos) demonstrating algorithmic errors in geoeconomic zones (Zonas Homogéneas Geoeconómicas), incorrect building score typologies, erroneous zoning restrictions, and topographical limitations.

Stopping Disproportionate Property Tax Spikes: The nationwide rollout of Colombia's Multipurpose Cadastre (Catastro Multipropósito) has triggered massive assessment increases that frequently exceed actual commercial value by 20% to 50%. Our technical contra-appraisals provide the unassailable evidence needed to rectify assessments and secure immediate tax relief.
  • Bogotá Cadastral Review (UAECD): Challenging inflated CHIP assessments across Chicó, Salitre, Calle 80, and industrial zones.
  • Medellín & Valle de Aburrá Reviews: Administrative review petitions before Subsecretaría de Catastro and AMVA municipalities.
  • Cali Municipal Cadastre Defense: Recalculating taxable bases under the Cali Municipal Tax Statute and POT norms.
  • Rural & Large-Acreage Adjustments: Removing conservation buffer zones, steep slope terrain, and non-arable acreage from urban tax formulas.
Cadastral assessment challenge and property tax review in Colombia PROPERTY TAX DEFENSE · UAECD · IGAC

Key Pericial Indicators · Cadastral & Tax Defense

Up to 35% Savings
Demonstrated historical reductions in overbilled cadastral valuations and annual tax bills
Statutory Deadlines
Administrative appeals filed within legal windows before local finance secretariats
CHIP & Geocoding
Correction of erroneous surface area records, building typologies, and strata
Art. 60 Law 1673
Certified technical contra-appraisal report accepted by IGAC and decentralized cadastres

Technical Valuation Framework

LegislationDecree 148/2020 · Law 14/1983 · IGAC Res. 1040/2023 · Law 1673/2013
DefenseRecurso de Reposición · Revisión de Avalúo Catastral · Silencio Administrativo
DeliverablesCertified Technical Contra-Appraisal Dossier · Legal Petition Brief for Tax Counsel
Substantial Tax Savings · Formal Recurso de Reposición Defense
/// FINANCIAL VALUATION PRACTICE · BUSINESS ENTERPRISE VALUE (DCF / WACC)

Business Enterprise Valuation, Intangibles & Goodwill (DCF / WACC)

Valuing ongoing operating businesses, corporate joint ventures, or standalone subsidiaries in Colombia requires sophisticated econometric modeling calibrated to local emerging market dynamics. Under IVS 200 (Businesses and Business Interests), our corporate finance practice delivers rigorous determinations of Enterprise Value (EV) and Equity Value for mergers and acquisitions, cross-border joint ventures, and tax reorganizations.

We execute Discounted Cash Flow (DCF) models with explicit 5-to-10 year projection horizons, calculating the Weighted Average Cost of Capital (WACC) through a modified Capital Asset Pricing Model (CAPM) that incorporates US risk-free benchmarks, levered industry betas, size premiums, and Colombia's sovereign risk spread (EMBI+). We also provide Purchase Price Allocation (PPA under IFRS 3 / ASC 805), identifying and valuing intangible assets—including customer relationships, brand trademarks, and proprietary software—along with annual IAS 36 Goodwill impairment tests.

Defensible Financial Valuation for M&A, Boards & Auditors: Combining macroeconomic rigorousness with deep Colombian sector insights, our financial valuation team models Enterprise Value (EV) and Equity Value under IVS 200, delivering non-redacted financial models accepted by investment banks, private equity funds, and Big Four auditors.
  • Mergers & Acquisitions (M&A) Due Diligence: Independent fairness opinions and valuation ranges for cross-border buyouts.
  • Purchase Price Allocation (PPA - ASC 805 / IFRS 3): Allocating acquisition premiums to tangible plant assets and identifiable intangibles.
  • Transfer Pricing & Intragroup Royalties: Relief-from-royalty and multi-period excess earnings method (MPEEM) for brand names and software.
  • Management Shareholder Buyouts & Fairness Opinions: Unbiased pericial determinations protecting minority shareholders during recapitalizations.
Business enterprise valuation, DCF financial modeling and WACC in Colombia ENTERPRISE VALUE · DCF / WACC · INTANGIBLES

Key Pericial Indicators · Corporate Finance & DCF

Dynamic WACC
Cost of equity via modified CAPM integrating country risk spread (EMBI Colombia)
10-Year Free Cash Flows
Unlevered free cash flow projections stress-tested against macro volatility
PPA & Intangibles (IFRS 3)
Purchase Price Allocation identifying trademarks, customer relationships & patents
IAS 36 Impairment Tests
Annual testing of goodwill and long-lived assets for corporate audit certification

Technical Valuation Framework

StandardsIVS 200 (Business and Business Interests) · IFRS 3 / ASC 805 · IFRS 13
MethodsDiscounted Cash Flow (DCF) · Market Multiples (EV/EBITDA, P/E) · Cost Approach
DeliverablesDynamic Financial Excel Model · Comprehensive Valuation Narrative · Sensitivity Matrix
IVS 200 & ASC 805 Compliant · Non-Redacted Working Excel Models
/// RAA CATEGORY 11 · FINE ART COLLECTIONS & COLOMBIAN EMERALDS

Fine Art Collections, Rare Gems & Colombian Emeralds Valuation

Valuing museum-grade fine art, historic numismatics, private luxury estates, and natural Colombian emeralds requires rare forensic scholarship paired with global auction market intelligence. Our certified appraisers in RAA Category 11 (Obras de Arte, Orfebrería y Joyas) operate under IVS 210 (Intangible Assets and Art Collectibles) and strict International Council of Museums (ICOM) ethics codes.

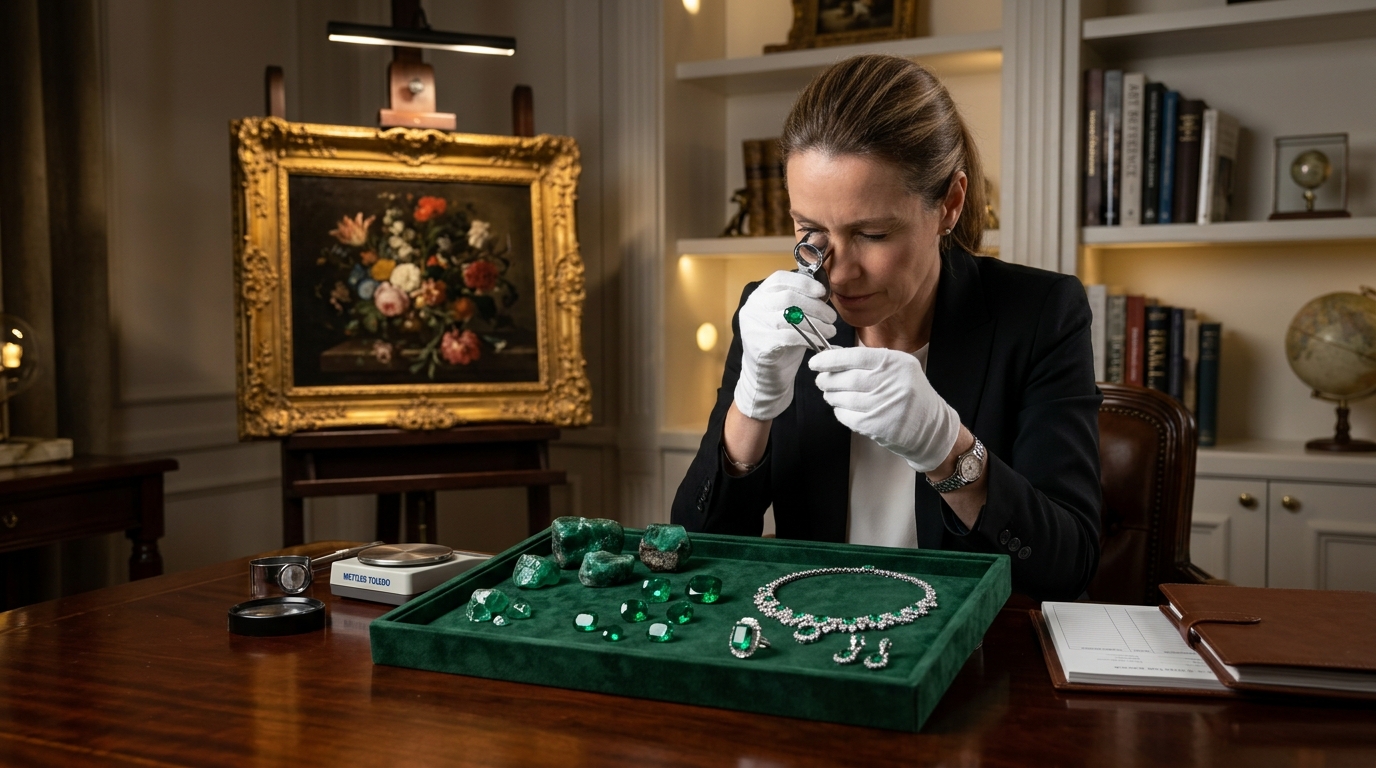
For fine art, we cross-reference auction records from Sotheby's, Christie's, and Latin American regional auction houses, verifying condition, forensic medium analysis, signature authenticity, and inclusion in official catalog raisonné volumes for prominent Colombian masters including Fernando Botero, Alejandro Obregón, David Manzur, and Débora Arango. For natural Colombian emeralds from Muzo, Chivor, and Coscuez, we collaborate with certified gemological laboratories (CDTEC, GIA, Gubelin) to appraise clarity enhancements, color saturation grades, and carat market premiums.

Uncompromising Discretion for High-Value Tangible Wealth: Masters of Colombian modernism (Fernando Botero, Alejandro Obregón, David Manzur, Débora Arango) and world-renowned Colombian emeralds from the Muzo, Chivor, and Coscuez belts require forensic expertise, international auction comparables, and certified gemological laboratory testing (CDTEC / GIA).
  • Paintings & Sculptures of Colombian & Latin Masters: Certified condition reports, catalog raisonné authentication cross-referencing, and market tracking.
  • Natural Colombian Emeralds & High Jewelry: Origin validation, clarity enhancement classification (none / minor / moderate oil), and replacement valuation.
  • Corporate & Private Museum Collections: Insurance scheduling, institutional gifting appraisals, and foundation tax compliance.
  • Estate Settlements & High-Net-Worth Portfolios: Impartial forensic appraisals safeguarding equitable distribution among heirs.
Fine art, Colombian emeralds and luxury estate appraisal in Colombia FINE ART · EMERALDS (MUZO/CHIVOR) · HIGH JEWELRY

Key Pericial Indicators · Fine Art & Gemology

Forensic Provenance
Scientific condition reporting, UV light analysis & historical exhibition documentation
Muzo & Chivor
Gemological grading of clarity, minor oil enhancement, color saturation & carat origin
Global Auction Sales
Pricing econometric models cross-referencing Sotheby's, Christie's & regional sales
3 to 5 Days
Confidential insurance appraisals, vault inspection & estate partition dossiers

Technical Valuation Framework

StandardsRAA Category 11 · IVS 210 · ICOM Code of Ethics · CDTEC Lab Reports
ForensicsUV Pigment Analysis · Spectroscopic Gem Analysis · Provenance Chain Verification
DeliverablesIllustrated Forensic Dossier · High-Value Insurance Slip Certificate
CDTEC & GIA Certified Gemology · Forensic Auction Benchmarks
SCIENTIFIC RIGOR & NORMATIVE GOVERNANCE

Official Valuation Methodologies & International Standards (Res. IGAC 941/2026)

Discover the specific mathematical formulation, economic foundation, and statutory accounting scope applied to each asset category across Colombia.

Valuation Approach Applicable RAA Categories Technical Basis & Mathematical Formulation International Standards Primary Institutional Uses
1. Market / Sales Comparison Approach Market Approach Urban Real Estate, Rural Lands, Commercial Fleets & Fine Art Statistical homogenization of contemporaneous market transactions utilizing correction matrices for usable area, prime location, bargaining spread, and physical vintage. IVS 105 (Market Approach) / USPAP Standards 1 & 7 Commercial acquisitions, syndicated mortgage collateral, Big Four fair value benchmarks, and market price determination.
2. Depreciated Replacement Cost (DRC) Cost Approach Industrial Machinery, Production Lines, Common Areas (Law 675) & Specialized Plants DRC = RCN × (1 - D). Replacement Cost New minus physical wear, functional and economic obsolescence modeled via Ross-Heidecke engineering tables. IVS 105 (Cost Approach) / IAS 16 (Property, Plant & Equipment) All-risk property casualty insurance policies, IFRS fixed asset impairment, and specialized facilities lacking active secondary markets.
3. Income Capitalization / DCF Approach Income Approach Hotels, Prime Offices, Shopping Malls, REITs/FICIs & Going Concerns Value = ∑ [FCF_t / (1 + WACC)^t] + Terminal Value. Discounting projected net operating cash flows over a 10-year horizon discounted at sovereign-risk adjusted WACC. IVS 105 (Income Approach) / IFRS 13 / US GAAP ASC 820 (Level 3 Inputs) Institutional real estate syndications, private equity M&A transactions, goodwill impairment tests, and enterprise valuations.
4. Static & Dynamic Residual Method Residual Technique Urban Land Lots, Expansion Parcels & Master-Planned Development Projects Deduction of raw land value from projected gross development revenue minus construction hard costs, soft costs, municipal charges, financing fees, and developer profit. IVS Guidance Note 12 (Development Property) / Municipal POT Zoning Codes Urban parcel acquisition, master plan feasibility underwriting, municipal betterment capture (plusvalías), and expropriation indemnities.
FREQUENTLY ASKED QUESTIONS

Institutional Valuation Questions & Technical Answers

Comprehensive regulatory, accounting, and procedural guidelines for multinational corporations, audit partners, and legal counsels operating in Colombia.

Submit a Specific Inquiry →
How do dual-compliant USPAP, IFRS 13 Fair Value, US GAAP ASC 820, and Colombian RAA appraisals work for multinational corporations?

Multinational corporations, foreign private equity funds, cross-border banking syndicates, and institutional investors operating in Colombia require valuation reports that simultaneously comply with Colombian statutory law (Law 1673 of 2013 and IGAC Resolution 941 of 2026) and withstand rigorous scrutiny from Big Four audit teams (PwC, EY, Deloitte, KPMG), the SEC, and international credit committees.

Domestic appraisal reports prepared exclusively for local mortgage or municipal purposes routinely fail external audits because they omit Level 2 versus Level 3 Fair Value classifications, lack econometric regression models for sales adjustments, omit formal Highest and Best Use (HBU) four-test validations, and fail to provide auditable Weighted Average Cost of Capital (WACC) derivations. Goods & Services Consulting S.A.S. bridges this divide through senior partners who are active members of the Appraisal Institute (United States) and licensed across all 13 categories of Colombia's Registro Abierto de Avaluadores (RAA).

Every report explicitly defines the standard and premise of value—Market Value under FIRREA and IVS 104, Fair Value under IFRS 13 and ASC 820, Depreciated Replacement Cost under IAS 16, or Orderly Liquidation Value (OLV) for credit facilities. We provide non-redacted, fully functional mathematical Excel deliverables alongside certified bilingual narrative reports.
What legal requirements make an appraisal valid under Colombian Law 1673 of 2013 and Resolution IGAC 941 of 2026?

Under Colombian Law 1673 of 2013 and Decree 556 of 2014, any appraisal presented before financial entities, judicial courts, notaries, or state authorities must be executed by an appraiser registered in the Registro Abierto de Avaluadores (RAA) administered by a recognized Self-Regulatory Organization (Entidad Reconocida de Autorregulación - ERA, such as ANA or ANAV).

Furthermore, Resolution IGAC 941 of 2026 mandates strict technical minimums: explicit identification of the appraiser's RAA license number and sub-specialty category, photographic and spatial geocoding (coordenadas georreferenciadas MAGNA-SIRGAS), full market data sheets for all comparative samples utilized, step-by-step econometric homogenization matrices with mathematical coefficients, zoning verification against the local municipal Territorial Ordering Plan (POT), and a minimum one-year validity guarantee.

How do you conduct fixed asset physical inventories and barcode/RFID tagging for ERP reconciliation (SAP, Oracle, Dynamics)?

Our fixed asset management methodology follows a disciplined five-stage engineering workflow: (1) Pre-inventory extraction and schema cleansing of the corporate fixed asset ledger from your ERP system (SAP S/4HANA, Oracle Cloud, Microsoft Dynamics 365, JD Edwards); (2) Field deployment of specialized technical crews equipped with rugged industrial mobile computers and thermal/laser imaging to physically count, describe, categorize, and tag each asset with anodized aluminum barcode plates or UHF RFID tags; (3) Asset componentization under IAS 16 Property, Plant and Equipment, separating composite installations into major depreciable parts; (4) Forensic ledger-to-floor reconciliation identifying matched items, ghost assets (activos fantasma), unrecorded capital enhancements, and location transfers; and (5) Delivery of validated upload-ready import templates and depreciation policy documentation.

What is the difference between Commercial Market Value and Insurable Replacement Cost New (VRN) under NSR-10?

Commercial Market Value represents the estimated amount for which an asset should exchange on the valuation date between a willing buyer and a willing seller in an arm's length transaction after proper marketing. Crucially, commercial real estate market value includes the non-insurable commercial value of the underlying land and accounts for accumulated physical, functional, and locational depreciation.

Conversely, Insurable Replacement Cost New (Valor de Reposición a Nuevo - VRN) measures the gross financial investment required to reconstruct the identical or functionally equivalent physical structure from the foundation up using contemporary construction techniques and materials. VRN explicitly excludes raw land value, excludes foundation elements below lowest basement level (where excluded by policy wording), and includes mandatory cost components that commercial market appraisals ignore: hazardous debris removal, demolition costs, professional architectural and engineering design fees, municipal building permits, and seismic structural code retrofits required under Colombia's NSR-10 seismic safety regulations.

How do you determine Fair Value for biological assets and agro-industrial facilities under IAS 41 and IAS 16?

Under international accounting standards, agro-industrial entities must split their operational assets into two distinct regulatory treatments: IAS 41 (Agriculture) for biological assets and IAS 16 (Property, Plant and Equipment) for bearer plants and processing infrastructure.

For consumable biological assets (such as standing sugarcane, commercial livestock, or harvestable field crops), Fair Value is determined under IAS 41 using the Net Realizable Value approach: projected market yield at physical harvest multiplied by market commodity spot prices, minus estimated transport and harvesting costs. For bearer plants (such as oil palm, citrus orchards, rubber, and coffee bushes), they are treated under IAS 16 at cost or revalued amount through their immature growth phase, followed by systematic depreciation over their commercial productive life. Processing plants (sugar mills, extraction plants, irrigation reservoirs) are appraised using Depreciated Replacement Cost combined with residual earnings models that capture environmental water concession values (concesiones de agua).

How are business enterprise valuations executed under IVS 200 and how is the WACC calculated for Colombian companies?

Business valuations are conducted in accordance with IVS 200 (Businesses and Business Interests). Our primary valuation approach is the Discounted Cash Flow (DCF) methodology, corroborated by the Guideline Public Company Method and Precedent Transaction Multiples (EV/EBITDA, EV/Sales).

To determine the discount rate for Colombian enterprises, we construct an auditable Weighted Average Cost of Capital (WACC). The Cost of Equity (Ke) is derived via a modified Capital Asset Pricing Model (CAPM): Ke = Rf + Beta*(Rm - Rf) + Alpha + Country Risk Premium. We source the risk-free rate (Rf) from US 10-Year Treasuries, re-lever industry betas based on target capital structures, and incorporate Colombia's sovereign risk spread (JP Morgan EMBI+ Colombia) alongside an empirical size premium (Duff & Phelps / Kroll data). Cash flows are modeled in both Colombian Pesos (COP) and US Dollars (USD) using purchasing power parity inflation differentials.

Can an appraisal be used to dispute an inflated property tax assessment (avalúo catastral) before IGAC or UAECD?

Yes. Under Article 60 of Colombian Law 1673 of 2013, Law 14 of 1983, and Decree 148 of 2020, any property owner or corporate taxpayer has the statutory right to request a formal administrative review of their cadastral appraisal (revisión de avalúo catastral) if they demonstrate that the official cadastral value exceeds commercial market value or fails to reflect physical, topographical, or legal encumbrances.

Goods & Services Consulting prepares certified technical contra-appraisals (contra-avalúos) specifically engineered for submission before the Unidad Administrativa Especial de Catastro Distrital (UAECD) in Bogotá, the Instituto Geográfico Agustín Codazzi (IGAC), or decentralized municipal cadastres in Medellín, Cali, and Barranquilla. Our reports demonstrate errors in geoeconomic zoning, incorrect construction age/score typologies, or excessive density assumptions, securing substantial property tax savings.

What standards apply to heavy machinery appraisals under IVS 300 and how is obsolescence calculated?

Industrial machinery and plant equipment appraisals follow IVS 300 (Plant and Equipment) and Colombian RAA Category 7. The primary valuation methodology is the Depreciated Replacement Cost (DRC) approach.

To quantify depreciation with engineering rigor, we apply the Ross-Heidecke model. Physical depreciation is calculated as a function of the machine's chronological age relative to its total economic useful life, modified by a five-stage maintenance and operational condition coefficient. Functional obsolescence is modeled by comparing operating costs, energy consumption, and output speed against contemporary machinery. Economic obsolescence is assessed by evaluating sector capacity utilization, regulatory compliance costs, and tariff shifts. We establish both In-Use values and Orderly Liquidation Values (OLV).

What are the procedural requirements for an expert witness appraisal report in Colombian commercial litigation (CGP Art. 226)?

Under Article 226 of the Código General del Proceso (Ley 1564 de 2012), an expert witness report (dictamen pericial) must comply with strict evidentiary standards: the appraiser must attach all university credentials, professional licenses, and RAA certifications demonstrating expertise in the specific subject matter; swear under oath that they have no conflict of interest or disqualifying relationship with the parties; provide detailed descriptions of the documents, inspections, and technical experiments conducted; cite all scientific, mathematical, and market sources relied upon; and state the conclusion with absolute logical and technical clarity.

Our senior partners regularly testify as expert witnesses in complex corporate litigation, expropriation indemnification cases (expropiación judicial), shareholder disputes, and international arbitrations, defending our reports under oral cross-examination.

What is the delivery turnaround time and what final deliverables are included in a certified appraisal dossier?

Turnaround time varies according to the scale and complexity of the asset portfolio: standard commercial real estate properties, offices, and individual industrial plants are typically delivered within 3 to 5 business days following the on-site physical inspection; complex industrial complexes, extensive multi-site fixed asset inventories, and business enterprise DCF valuations require between 5 to 15 business days.

Final deliverables comprise: (1) A comprehensive certified narrative appraisal report in Spanish, English, or bilingual presentation; (2) The appraiser's official RAA certificate and Self-Regulatory Organization (ERA) registration badge; (3) High-resolution photographic inspection annexes and geographic geocoding maps; (4) Fully functional, non-redacted mathematical Excel calculation models containing all formulas; and (5) Executive certification summaries suitable for direct submission to banking credit committees, external audit firms, or judicial dockets.

/// INSTITUTIONAL VALUATION PROPOSALS · BILINGUAL DESK

Request an Official Valuation Proposal in Colombia

Direct engagement with accredited RAA partners and registered valuation engineers. Dual-certified reports accepted by international banks, Big Four audit firms (PwC, EY, Deloitte, KPMG), M&A boards, and arbitration tribunals.

20+ Years of Pericial Leadership Founded in 2006, leading institutional appraisals across Colombia's 32 departments.
RAA Certified Appraisers (Law 1673 & Res. IGAC 941/2026) Full statutory accreditation across all 13 official valuation categories.
Dual Compliance: USPAP, IVS, IFRS 13 & US GAAP ASC 820 Rigorous technical standards accepted worldwide for cross-border transactions and audits.
100% Bankable & Admissible in Commercial Courts Recognized by ASOBANCARIA lenders, global reinsurers, and CGP Art. 226 judicial dockets.

Request Formal Valuation Proposal

Complete the asset parameters below. A senior valuation partner will contact you within 2 business hours with a preliminary scope and fee proposal.

Strict Professional Non-Disclosure (NDA) Guaranteed · Proposal in < 2 Business Hours

Bogotá Principal Office

Carrera 15 # 88-21, Office 702
El Chicó / Parque El Virrey
Bogotá D.C., Cundinamarca

Direct: +57 (601) 745 8990

Medellín Regional Office

Carrera 43A # 1-50, Tower 2, Suite 804
San Fernando Plaza / Milla de Oro
Medellín, Antioquia

Direct: +57 (604) 605 2888

Cali Regional Office

Carrera 56 # 2-157, Tower 2, Office 505
Edificio Sottomonte / Cuarto de Legua
Cali, Valle del Cauca

Direct: +57 (602) 489 8990 / +57 317 639 4990