We appraise your industrial plant

Certified Appraisals in Colombia

Eliminate audit findings, bank rejections, and tax overpayments. Over 20 years of valuation leadership in Bogotá D.C., Medellín, and Cali delivering audit-ready reports under USPAP, IFRS 13, US GAAP, and Colombia's RAA / IGAC Res. 941.

IFRS & US GAAP fixed asset inventories, barcode tagging, industrial plants, Oil & Gas facilities, bank collateral, insurance replacement cost, and aircraft valuations—built for CFOs and Big Four audits.

RAA Certified IFRS · IVS · US GAAP 20+ Years Appraisal Institute (U.S.)
Proven Institutional Track Record · Founded in 2006

Trusted by Colombia's Most Demanding Enterprises, Regulators & Multinationals

With over 20 years of uninterrupted history and 15,000+ assets valued nationwide, our certified reports carry full legal authority before domestic and international banks, insurers, courts, tax authorities, and Big Four auditors under Law 1673, IFRS, IVS, and USPAP.

IGAC - National Geographic Institute of Colombia
DANE - National Administrative Department of Statistics
Grupo Energía Bogotá (GEB)
EAAB - Bogotá Water & Sewerage Utility
OPAIN S.A. - El Dorado International Airport
ANI - National Infrastructure Agency of Colombia
SAE - Special Assets Society of Colombia
INDUMIL - Colombian Military Industry
SATENA - Colombian State Airline
TransMilenio S.A. Bogotá Transit System
Colombian Geological Survey (SGC)
Supersubsidio - Superintendence of Family Subsidy
ADR - Rural Development Agency of Colombia
Bogotá District Secretariat of Government
GateGroup Global Aviation Catering
Perficient - Global Digital Consultancy
SUDECO Customs Brokerage Agency
Universidad del Tolima
AMB - Bucaramanga Metropolitan Water Utility

20+ Years of Valuation Excellence

Uninterrupted leadership since 2006 appraising corporate, industrial, and residential assets from offices in Bogotá D.C., Cali, and Medellín.

RAA-Accredited Appraisers

Officially registered in Colombia's Open Registry of Appraisers (Law 1673) across real estate, machinery, special assets, and business valuation.

USPAP, IFRS & IVS Standards

Active Appraisal Institute (U.S.) members delivering bilingual reports fully aligned with IFRS 13, IAS 16, IAS 36, US GAAP, and Big Four audit standards.

100% Bankable & Audit-Proof

Accepted nationwide by commercial banks, leasing institutions, global reinsurance underwriters, international investors, and civil courts.

Need to value assets in Colombia? Ask a Senior Appraiser directly.

Type your question below and connect instantly with a bilingual certified appraiser via WhatsApp.

Executive desk Monday–Friday (COT / EST). Direct line: +57 (317) 639 4990 · licitaciones@goodsyservices.com

One Unified Firm

One certified team protecting the full lifecycle of your assets in Colombia

We inspect, tag, reconcile, value, and monitor your physical and financial assets—delivering audit-ready reports for headquarters, banks, insurers, and courts.

0+years of experiencevaluing assets across Colombia
0specialized service linesfrom real estate to oil & gas
0regional headquartersBogotá & Cali · nationwide reach
0valuation frameworksUSPAP · IFRS · IVS · RAA
How We Work

From Field to Report: Verifiable Technical Rigor on Every Inspection

We inspect, tag, and value every asset directly at its operating site—manufacturing plants, corporate towers, logistics hubs, and oilfields.

On-Site Industrial InspectionReference operational footage
Our Valuation Practice

Certified Appraisals in Colombia Backed by Banks, Courts & Big Four Auditors

Defensible expert reports tailored to multinational corporations, institutional lenders, public entities, and private international owners.

CorporatePersonal

Real Estate Appraisals

Commercial, industrial, residential, and rural property valuations across Colombia under IGAC Resolution 941 of 2026, IVS 400, and USPAP. Trusted for acquisitions, mortgage collateral, REITs, and judicial proceedings.

Request real estate appraisal
Corporate

Machinery & Industrial Equipment

Manufacturing lines, yellow construction machinery, cranes, agricultural systems, and heavy plant equipment valued under IVS 300.

Request machinery appraisal
CorporatePersonal

Vehicle & Fleet Appraisals

Commercial transport fleets, specialized trucks, luxury vehicles, and passenger cars with physical inspection and verified market benchmarks.

Request fleet valuation
Corporate

Business & Equity Valuation

Enterprise value, M&A Purchase Price Allocation (ASC 805 / IFRS 3), goodwill impairment, and WACC Discounted Cash Flow models.

Request business valuation
Corporate

IFRS Fixed Asset Inventory & Valuations

End-to-end physical verification, IAS 16 componentization, IAS 36 impairment testing, and IFRS 13 fair value reporting ready for Big Four audits and ERP integration.

Explore IFRS inventory
Personal

Judicial, Estate & Divorce Appraisals

Court-admissible expert witness reports (Law 1564 CGP) for inheritances, marital asset divisions, IRS estate filings, and commercial arbitration.

Request judicial appraisal
Corporate

Asset Tagging & Barcode / RFID Coding

Industrial anodized aluminum plates, tamper-proof 3M security labels, and UHF RFID tags for lifecycle fixed-asset control.

Explore asset tagging
Corporate

Fixed Asset Management Software

Real-time visibility into asset custody, cost-center location, depreciation schedules, and current fair value across all branches.

Explore asset software
PersonalCorporate

Fine Art & Private Collections

Paintings, sculptures, and Latin American masters appraised by provenance, conservation state, and Christie's/Sotheby's market benchmarks.

Request fine art appraisal
Personal

Fine Jewelry, Emeralds & Watches

Gold, platinum, GIA-graded diamonds, Swiss watches, and Muzo/Chivor Colombian emeralds valued for insurance, estates, or sales.

Request jewelry appraisal
CorporatePersonal

Insurance Replacement Cost (RCN)

Replacement Cost New valuations for industrial plants, office towers, and condominiums to set accurate insured sums and prevent underinsurance penalties.

Request insurance valuation
Corporate

Bank Collateral & Leasing Valuations

Initial collateral appraisals and periodic fair-value updates on real estate, heavy equipment, and industrial fleets for local and international lenders.

Request collateral appraisal
PersonalCorporate

Cadastral Value Review & Tax Appeals

Certified commercial appraisals serving as binding technical evidence to appeal inflated municipal property tax (Impuesto Predial) assessments.

Request cadastral review
Corporate

Agribusiness, Mills & Food Plants

Flour, rice, and corn mills, processing plants, and permanent plantations (IAS 16 / IAS 41) valued with landed import cost and FX calibration.

Request agribusiness appraisal
CorporatePersonal

Aircraft: Jets, Helicopters & Aviation Fleets

USD valuations analyzing airframe hours/cycles (TSN/CSN), engine overhaul status (TSOH), AD/SB compliance, avionics, and Aerocivil/FAA records for sales, leasing, hull insurance, and litigation.

Request aircraft appraisal
Oil & GasEnergy Infrastructure

Specialized Oil & Gas Industrial Assets

Production facilities, pipelines, API 650 storage tanks, processing plants, and drilling rigs—purpose-built assets without open comparables, valued under IVS 300 and API/ASME engineering standards.

Explore Oil & Gas specialty
Industry Solutions

Valuations Engineered for Your Sector

Every industry has distinct assets, regulatory regimes, and audit timelines. Select your sector to see how we deliver.

Smart Asset Control

Every fixed asset tagged, located, and IFRS-valued

Turnkey IFRS fixed asset inventory and reconciliation across Colombia: from physical site verification to ERP-ready valuation registers built for Big Four audits.

  1. 1

    On-Site Physical Count

    Field engineering teams inspect, photograph, and verify every tangible asset across your offices, warehouses, and plants.

  2. 2

    Industrial Barcode & RFID Tagging

    Durable anodized aluminum plates or tamper-evident 3M labels assign a permanent unique ID to every asset.

  3. 3

    IFRS Accounting Reconciliation

    We cross-match physical assets against your ERP ledger, resolve surpluses/missing items, and recalculate remaining useful lives.

  4. 4

    Audit Report & Asset Software

    Clean master database ready for SAP, Oracle, NetSuite, or Siigo with live tracking throughout each asset's economic lifecycle.

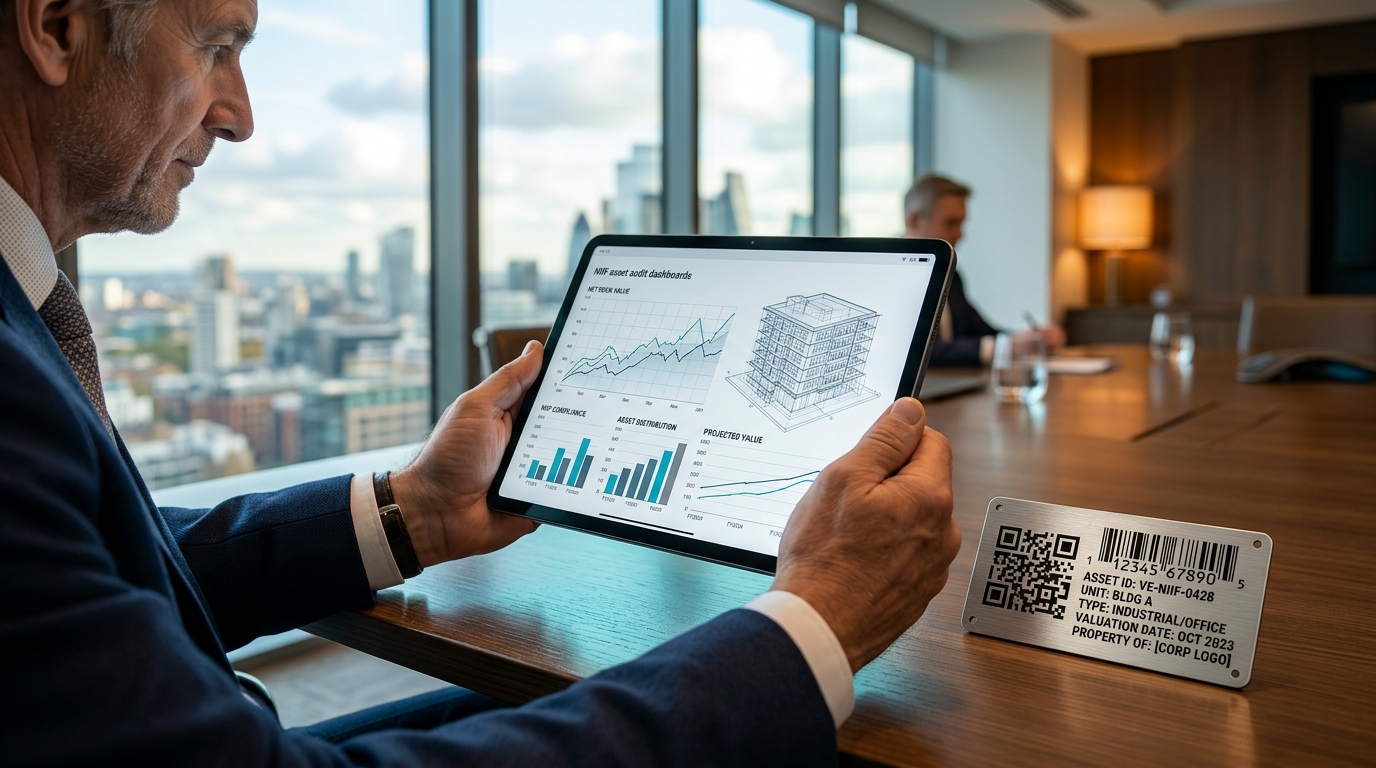
Senior appraiser reviewing IFRS fixed asset audit and barcode asset plate IFRS Audit · IAS 16 / IAS 36
Goods & ServicesIFRS FIXED ASSET
GYS-000127
GYS-000125Server Rack · Floor 3Reconciled
GYS-000126Forklift · WarehouseReconciled
GYS-000127CNC Line · Plant AReconciled

Process illustration. Sample asset plate codes shown.

Oil & Gas · Energy Practice

Specialized Industrial Asset Valuation for the Oil & Gas Sector

We appraise purpose-built hydrocarbon and energy assets with no active secondary market: processing plants, pipelines, tank farms, and upstream production facilities—applying IVS 300 methodologies under strict field HSE coordination.

  • Production facilities & gathering stations
  • Crude, gas & multi-product pipelines
  • API 650 storage tanks & tank farms
  • Drilling & workover rigs
  • Processing, compression & pumping plants
  • Power generation & substations
OIL & GAS · API 650 · ASME · HSE PROTOCOLS

Key Institutional Uses

  • IFRS & US GAAP reporting: IAS 16, IAS 36 & ASC 360 impairment
  • Energy insurance: Replacement Cost New (RCN) underwriting schedules
  • Farm-ins, M&A transactions, project finance & syndicated collateral
  • Litigation & petroleum right-of-way easements (Law 1274 of 2009)
  • Remaining reserve-life alignment & ARO abandonment cost modeling

Depreciated Replacement Cost

The IVS 300 cost approach for specialized assets without market comparables: modern equivalent installed cost minus physical wear, functional, and economic obsolescence.

Field Inventory & Tagging

On-site physical verification of every vessel, pump, and turbine with unique industrial tagging reconciled directly to the operator's fixed-asset register.

HSE-Compliant Fieldwork

Inspection campaigns seamlessly aligned with each operator's HSE inductions, safety permits, and site protocols across remote basins and refineries.

About Goods & Services

Behind every asset lies a dream. We protect its true value.

Founded in 2006, Goods & Services Consulting S.A.S. is a premier Colombian valuation firm with over 20 years of experience delivering commercial real estate, industrial, Oil & Gas, and IFRS/USPAP appraisals for multinational corporations, financial institutions, public entities, and private investors.

Our multidisciplinary team of RAA-certified engineers, architects, economists, and active Appraisal Institute (U.S.) members combines deep local Colombian market intelligence with global institutional reporting discipline.

  • Legally binding before banks, insurers, courts & Big Four auditors
  • Nationwide coverage from owned hubs in Bogotá D.C. & Cali
  • Bilingual executive delivery (English / Spanish) at every stage
Explore Our 20+ Year Track Record
Couple receiving keys to their new home in Colombia — certified appraisals protecting real wealth
“Your home, your plant, your portfolio: every asset tells a story. Our job is to establish and protect its true value.”
— Goods & Services Consulting S.A.S.
Clear Execution

Your Certified Appraisal in 4 Structured Steps

Transparent scope, predictable timelines, and senior guidance from engagement letter to final sign-off.

1

Scope & Proposal

Define intended use (USPAP, IFRS, lending, M&A, or tax) and receive a fixed-fee timeline proposal.

2

On-Site Inspection

An RAA-certified appraiser inspects the asset, verifies legal/title records, and captures georeferenced proof.

3

Technical Valuation

Market comparables, engineering DRC curves, and DCF models reconciled under IVS, IFRS, or USPAP.

4

Certified Delivery

Committee-reviewed bilingual PDF report and ERP/audit schedules ready for banks, auditors, or courts.

Why Goods & Services

Why Global Firms & Investors Choose Us in Colombia

Technical precision, dependable turnaround times, and dual Colombian–U.S. credibility that withstands the strictest institutional review.

Speed with Audit Precision

Reliable delivery aligned with M&A closings, credit committees, and fiscal year-end deadlines—never sacrificing evidentiary depth.

Nationwide Field Reach

Permanent offices in Bogotá D.C. and Cali, active teams in Medellín and Barranquilla, and mobile squads covering remote industrial and oilfield regions.

Dual International Credentials

Methodologies harmonized across USPAP, International Valuation Standards (IVS), IFRS 13/IAS 16/IAS 36, US GAAP, and Colombia's statutory RAA registry.

RAAIVSIFRSUS GAAPUSPAPAppraisal Institute
Cross-Border Standard

U.S.-Standard (USPAP & US GAAP) Appraisals in Colombia

Members of our senior valuation team belong to the Appraisal Institute (United States). We deliver English and bilingual appraisals compliant with USPAP, IVS, and US GAAP alongside full Colombian RAA statutory certification.

  • U.S. Multinational Subsidiaries in ColombiaFair Value (ASC 820), Purchase Price Allocation (ASC 805), and impairment testing (ASC 360) for SEC & Big Four audits.
  • U.S. Banks, Private Equity & Institutional InvestorsCollateral verification, acquisition due diligence, and portfolio mark-to-market valuations across Colombian assets.
  • U.S. Citizens & Expats Owning Property in ColombiaQualified fair market valuations supporting IRS estate and gift tax filings (Forms 706 / 709) and cross-border wealth planning.
  • Colombian Families with Cross-Border HoldingsIndependent valuation support for foreign-asset tax disclosures, international estates, and cross-jurisdictional settlements.
AIActive Members of the Appraisal Institute (United States)
USPAPUniform Standards of Professional Appraisal Practice
IVSInternational Valuation Standards (IVSC)
RAAColombia's Statutory Open Registry of Appraisers (Law 1673)
Engagement scope, currency (USD/COP), and reporting format are tailored to intended use and auditor requirements.
Technical Library & Regulatory Guides

Valuation Research, IFRS Compliance & Colombian Market Briefings

Explore our senior research briefings on IGAC Resolution 941 of 2026, IFRS/US GAAP fixed asset audits, Oil & Gas valuation standards, and prime real estate corridors.

USPAP & US GAAP

USPAP & ASC 820 Valuations for U.S. Subsidiaries in Colombia

How Appraisal Institute standards align with Colombia's RAA framework to satisfy SEC filings, Big Four audits, and cross-border lending.

Read technical brief →
IFRS Accounting

Year-End Fixed Asset Valuations: IAS 16, IAS 36 & IFRS 13

Step-by-step audit guide to componentization, technical remaining useful lives, impairment testing, and SAP/Oracle physical reconciliation.

Read IFRS guide →
IGAC Regulation 2026

IGAC Resolution 941 of 2026 vs. Resolution 620 of 2008

Breakdown of the 12 mandatory legal and statistical elements every commercial appraisal in Colombia must satisfy to remain binding.

Read regulatory brief →
Foreign Investment

Real Estate Due Diligence in Bogotá, Medellín & Cali

Navigating closed-price opacity, POT zoning rules, short-term rental (RNT) premiums in El Poblado, and title verification for foreign buyers.

Read investor guide →
Oil & Gas Sector

Valuing API 650 Tanks, ASME B31.4 Pipelines & EPF Assets

Engineering Depreciated Replacement Cost (IVS 300) integrated with 1P/2P reserve life limits and ANH concession abandonment liabilities.

Explore Oil & Gas →
Risk & Insurance

Replacement Cost New (RCN) & Preventing Underinsurance

Why book value exposes Colombian plants and condominiums to proportional co-insurance penalties under Commercial Code Article 1102.

Read insurance brief →
Tax Optimization

Appealing Inflated Cadastral Property Taxes (Impuesto Predial)

How certified commercial appraisals under IGAC Resolution 1149 of 2021 establish legal proof to reduce excessive municipal tax assessments.

Read tax appeal guide →
Industrial Engineering

Machinery & Plant Valuation: Landed Cost & Obsolescence

Modeling FOB/CIF import costs, installation, Ross-Heidecke wear curves, and going-concern vs. orderly liquidation premises.

Read industrial brief →
Special Assets

Aviation, Fine Art & GIA-Graded Colombian Emeralds

International USD benchmarking for corporate aircraft, museum-grade Latin American art, and Muzo/Chivor emeralds for insurance and estates.

Read special assets guide →
Technical Knowledge Base

Frequently Asked Questions on Appraisals in Colombia

International standards (USPAP, IFRS 13, US GAAP), Colombian statutory law (RAA & IGAC Res. 941 of 2026), Oil & Gas methodologies, foreign real estate due diligence, and turnaround protocols—answered in depth by our senior appraisers.

Consult a Senior Appraiser Directly
USPAP · US GAAP · Appraisal InstituteHow does a USPAP-compliant appraisal work in Colombia for U.S. multinationals, Big Four audits, and IRS filings?
Executive Summary

U.S. multinationals, private equity funds, commercial banks, and cross-border family offices operating in Colombia frequently require valuation reports that satisfy both Colombian statutory law and U.S. federal appraisal standards. Our Appraisal Institute members deliver dual-compliant bilingual reports aligned with USPAP, IVS, US GAAP, and Colombia's RAA framework.

1. Why Local Colombian Appraisals Alone Often Fail U.S. Audit Review

In cross-border financial reporting and institutional lending, a standard local valuation prepared exclusively for municipal or retail mortgage purposes rarely satisfies the scrutiny of U.S. headquarters, Big Four audit partners, or the Securities and Exchange Commission (SEC). The Uniform Standards of Professional Appraisal Practice (USPAP)—promulgated by The Appraisal Foundation under federal authority (FIRREA)—impose strict rules on ethics, competency, scope of work, market evidence, and quantitative reconciliation that exceed ordinary descriptive reports.

At Goods & Services Consulting S.A.S., our valuation team includes active members of the Appraisal Institute (United States) alongside senior appraisers registered in Colombia's Registro Abierto de Avaluadores (RAA). This dual qualification allows us to issue authoritative reports in English or bilingual English/Spanish format without requiring expensive foreign travel or disconnected local subcontractors.

2. Core Technical Requirements of a USPAP & US GAAP Engagement

  • Explicit Basis and Premise of Value: Every engagement clearly defines whether the conclusion reflects Market Value (per OCC, FDIC, and Federal Reserve definitions), Fair Value under ASC 820 (Fair Value Measurement), Insurable Replacement Cost, or Orderly/Forced Liquidation Value, specifying the Fair Value Hierarchy level (Level 2 or Level 3 inputs) required by external auditors.
  • Rigorous Highest and Best Use (HBU) Analysis: USPAP requires an independent four-test evaluation—legally permissible under the municipal Land Use Plan (POT), physically possible, financially feasible, and maximally productive—both "as vacant" and "as improved." For industrial warehouses or legacy commercial parcels in Bogotá, Medellín, or Cali undergoing urban redevelopment, HBU directly governs residual land value.
  • Reconciliation of All Three Valuation Approaches: Where applicable, we develop and transparently reconcile the Sales Comparison Approach, the Cost Approach (with physical deterioration, functional obsolescence, and external obsolescence explicitly quantified), and the Income Capitalization Approach (using market-supported cap rates and WACC-derived Discounted Cash Flow models).
  • USPAP Certification & Independence Statement: Every report includes the mandatory signed certification confirming zero financial interest in the subject asset, non-contingent professional fees, and full ethical independence.

3. Primary Cross-Border Use Cases in Colombia

  1. US GAAP Financial Consolidation & M&A: Purchase Price Allocation (ASC 805), long-lived asset impairment testing (ASC 360), and annual fair value mark-to-market reporting for U.S.-listed parent companies with subsidiaries in Colombia.
  2. Cross-Border Banking & Private Credit: Collateral due diligence for U.S. commercial banks, multilateral lenders, and institutional debt funds financing real estate, logistics parks, energy infrastructure, or industrial machinery in Colombia.
  3. IRS Estate, Gift & Expatriation Tax Compliance: Qualified appraisals supporting Form 706, Form 709, and cross-border wealth disclosures for U.S. citizens holding real estate or equity stakes in Colombia, or Colombian residents holding U.S. assets.
Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
IFRS 13 · IAS 16 · IAS 36Why do multinational subsidiaries in Colombia require physical fixed asset inventories and IFRS 13 / IAS 16 / IAS 36 valuations?
Executive Summary

Under Colombia's mandatory IFRS adoption framework (Law 1314 of 2009 and Regulatory Decree 2420 of 2015), corporations can no longer rely solely on historical tax depreciation tables. Audit-ready financial statements require physically reconciled asset registers, technical componentization, accurate remaining useful lives, and defensible Fair Value measurements under IFRS 13.

1. Closing the Gap Between Tax Books and Economic Reality

Many operating subsidiaries in Colombia inherit fixed asset ledgers accumulated over decades of acquisitions, capex projects, and plant relocations. Over time, ERP sub-ledgers drift away from physical reality: decommissioned equipment remains on the balance sheet ("ghost assets"), newly capitalized machinery lacks serial traceability, and assets are depreciated using generic Colombian tax rates (Article 137 of the Tax Statute) rather than their actual economic life. During year-end Big Four audits, these discrepancies trigger audit qualifications, internal control findings, and distorted EBITDA or return-on-assets metrics.

Goods & Services Consulting S.A.S. delivers an integrated, end-to-end solution combining physical field verification, durable barcode or RFID asset tagging, accounting reconciliation, and certified IFRS valuation—producing clean master data ready for direct upload into SAP, Oracle, NetSuite, Microsoft Dynamics, Siigo, or Novasoft.

2. Five Core IFRS Standards Addressed in Every Engagement

  • IAS 16 (Property, Plant and Equipment) — Revaluation & Componentization: We establish Fair Value for land, buildings, and specialized machinery, while breaking complex properties into significant components with distinct useful lives (structural shell, HVAC, elevators, electrical substations, roofs, and specialized process lines) to ensure accurate depreciation expense.
  • Technical Remaining Useful Life (RUL) & Residual Value: Rather than applying static 10- or 45-year tax schedules, our engineers inspect maintenance logs, operating hours, and technological wear to assign evidence-based remaining useful lives and salvage values.
  • IAS 36 (Impairment of Assets): Whenever economic headwinds, idle plant capacity, or regulatory shifts indicate potential impairment, we determine the Recoverable Amount—the higher of Fair Value Less Costs of Disposal (FVLCD under IFRS 13) and Value in Use (DCF modeling per Cash-Generating Unit, CGU)—providing auditors with transparent sensitivity tables.
  • IAS 40 (Investment Property) & IFRS 5: Recurring fair value determinations for income-producing commercial portfolios, logistics hubs, and non-current assets held for sale.
  • IAS 41 & IAS 16 (Agribusiness & Bearer Plants): Specialized separation of bearer plants (oil palm, coffee, sugarcane, Hass avocado plantations) under IAS 16 from biological agricultural produce valued at fair value less costs to sell under IAS 41.

3. Physical Tagging & Four-Way ERP Reconciliation

Our field crews tag every verifiable asset using anodized aluminum barcode plates (resistant to heat, solvents, and industrial abrasion), tamper-evident 3M polyester labels, or passive UHF RFID tags. We then execute an automated reconciliation against the client's fixed asset sub-ledger, classifying 100% of items into Matched Assets, Physical Surpluses, Missing Assets, and Fully Depreciated Assets Still in Active Use, accompanied by recommended journal entries for audit sign-off.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Foreign Investors · Bogotá · Medellín · CaliWhat must foreign buyers, expats, and investment funds know about commercial and residential real estate valuations in Bogotá, Medellín, and Cali?
Executive Summary

Colombia does not have a unified MLS database of closed real estate transactions, and asking prices on public listing portals often diverge by 15% to 35% from true closing values. An independent RAA-certified appraisal protects foreign buyers, REITs, and corporate tenants from overpaying, zoning traps, seismic liabilities, and title defects.

1. Overcoming Information Asymmetry in Colombia's Property Market

Unlike the United States or Western Europe, where public county records and MLS platforms publish verified closing prices per square foot, Colombian deeds frequently reflect cadastral or negotiated figures that obscure true market pricing. Relying on broker estimates or unverified online listings exposes foreign buyers and institutional investors to severe overpayment, especially in high-demand neighborhoods targeted by international capital.

Our appraisers maintain proprietary, continuously updated market comparables across Colombia's three premier urban economies—applying econometric homogenization matrices, verified closed-sale intelligence, and local land-use expertise under IGAC Resolution 941 of 2026 and IVS 400 (Real Property Interests).

2. City-by-City Market & Regulatory Dynamics

  • Bogotá D.C. (Decree 555 of 2021 — POT "Bogotá Reverdece"): Colombia's financial and corporate capital features prime office and diplomatic corridors in Chicó, Parque 93, El Nogal, Rosales, and Usaquén, alongside premier Class-A logistics parks along Calle 80, Fontibón, and Siberia. Valuations must scrutinize urban renewal zoning ("Actuaciones Estratégicas"), land-value capture taxes (Participación en Plusvalía), soft-soil seismic microzonation (Decree 523 of 2010), and potential public-works takings linked to the Bogotá Metro and IDU corridors.
  • Medellín & Aburrá Valley (Agreement 48 of 2014): In El Poblado, Laureles, Envigado, Sabaneta, and Llanogrande (Rionegro), steep valley topography creates structural land scarcity. Crucially, properties legally zoned and authorized in their Homeowners Association bylaws (Reglamento de Propiedad Horizontal) for short-term tourist rentals (Airbnb / RNT) command a 15% to 30% valuation premium over restricted residential units—yet unauthorized short-term rental assumptions can collapse an investment thesis overnight.
  • Cali & Valle del Cauca (Agreement 0373 of 2014): As the Pacific coast's industrial and agribusiness gateway, Cali combines high-end residential appreciation in Pance, Ciudad Jardín, El Peñón, and San Fernando with strong industrial warehouse demand in Acopi Yumbo and Menga. Because Cali lies in a high seismic hazard zone, compliance with Colombia's seismic building code (NSR-10) and geotechnical stability directly impacts both Fair Market Value and insurability.

3. Legal & Technical Due Diligence Embedded in Every Valuation

Before issuing a valuation conclusion, our team verifies the official Certificado de Tradición y Libertad (title history), public deed boundaries, horizontal property co-ownership coefficients (Law 675 of 2001), municipal zoning certificates, and unpermitted expansions—ensuring foreign capital enters every transaction with institutional-grade clarity and bankable security.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Oil & Gas · API 650 · ASME · ANHHow are Oil & Gas surface facilities, API 650 storage tanks, pipelines, and energy infrastructure valued in Colombia?
Executive Summary

Upstream, midstream, and energy infrastructure assets across Colombia's Llanos Orientales, Magdalena Medio, Putumayo, and Caribbean basins are purpose-built specialized assets with no active secondary sales market. Valuing them requires combining IVS 300 Depreciated Replacement Cost with petroleum engineering standards (API, ASME, NACE) and ANH concession economics.

1. Specialized Valuation Methodology for Non-Marketable Energy Assets

Oil and gas facilities cannot be appraised using ordinary real estate comparables. Operators, joint-venture partners, lenders, and external auditors require engineering-driven valuations built from the ground up using the Depreciated Replacement Cost (DRC) methodology under IVS 300 (Plant and Equipment), cross-checked against Discounted Cash Flow (DCF) economic ceilings under IAS 36 / ASC 360. At Goods & Services Consulting S.A.S., our multidisciplinary field teams—operating under strict client HSE (Health, Safety & Environment) protocols—inspect remote production stations, refineries, tank farms, and compressor sites nationwide.

2. Component-Level Engineering Analysis

  • Atmospheric & Pressurized Storage Tanks (API 650 / API 12F / ASME Sec. VIII): We quantify structural steel tonnage across shell courses, floor plates, floating or cone roofs, internal heating coils, fire-suppression foam systems, telemetry instrumentation, and secondary environmental containment bunds. Physical depreciation incorporates ultrasonic non-destructive thickness testing (NDT) data to accurately capture internal and external corrosion loss.
  • Flowlines, Gathering Systems & Pipelines (ASME B31.4 / B31.8): Valuation models calculate installed cost per kilometer by nominal diameter and wall thickness (Schedule), integrating carbon-steel pipe pricing (API 5L Grade B, X52, X65), FBE or three-layer anti-corrosion coatings, right-of-way (ROW) acquisition, trenching in rocky or flood-prone terrain, radiographed welds, hydrostatic testing, cathodic protection, and booster pumping stations.
  • Early Production Facilities (EPF), Separation & Compression: Two- and three-phase API 12J separators, heater treaters, gas boots, flare stacks, reciprocating or screw gas compressors, water-injection plants for secondary recovery, and power-generation turbines/substations.
  • Drilling & Workover Rigs: Technical verification of mast capacity, drawworks, mud pumps, blowout preventers (BOP), top drives, engine hours, and API recertification status.

3. Reserve Life Cap, ANH Concessions & Asset Retirement Obligations

A decisive factor in Oil & Gas valuation is Economic Obsolescence tied to hydrocarbon reserves. No surface facility can hold an economic useful life exceeding the remaining commercial life of the field's proved (1P) and probable (2P) reserves or the concession term granted by Colombia's Agencia Nacional de Hidrocarburos (ANH). Our reports integrate field decline curves, decommissioning and site-abandonment provisions (IAS 37 / ASC 410 ARO), and statutory petroleum right-of-way easements under Law 1274 of 2009.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Machinery · Plant & Equipment · IVS 300How are industrial machinery, manufacturing plants, and heavy yellow equipment valued under IVS 300 and Depreciated Replacement Cost?
Executive Summary

Industrial machinery and manufacturing lines represent a major share of corporate balance sheets and bank collateral in Colombia. Our RAA-certified engineering appraisers determine Fair Market Value in Continued Use, Orderly Liquidation Value, and Forced Liquidation Value by integrating landed import costs, mechanical wear, and technological obsolescence.

1. Calculating True Landed Replacement Cost New (RCN)

Accurately valuing industrial machinery in Colombia requires far more than looking up an overseas manufacturer's catalog price. Most specialized production equipment—CNC machining centers, plastic extrusion lines, flour and rice milling systems, pharmaceutical packaging lines, gantry cranes, and yellow construction equipment (excavators, bulldozers, loaders)—is imported in USD or EUR. Under IVS 300, we build the Replacement Cost New (RCN) from verified primary OEM quotes plus all direct and indirect capitalization costs required to bring a modern equivalent asset into operation in Colombia:

  • Landed Acquisition & Logistics: Ex-Works / FOB equipment cost, international maritime or air freight, marine transit insurance, Colombian customs duties, non-recoverable VAT, brokerage fees, and inland heavy-haul transport to the plant site.
  • Installation & Commissioning: Specialized reinforced concrete foundations, electromechanical assembly, industrial piping and wiring, PLC/SCADA automation integration, engineering design fees, and pre-operational commissioning tests.

2. Quantifying All Three Forms of Depreciation & Obsolescence

  1. Physical Deterioration: Assessed through mandatory on-site inspection of manufacturer serial plates, hour meters, maintenance logs, vibration/wear patterns, and exposure to corrosive environments. We model loss of value using recognized engineering curves (Ross-Heidecke and age-life effective-age ratios) calibrated to observed condition.
  2. Functional Obsolescence: Measures the penalty of operating older technology compared to a modern equivalent asset—factoring in excess energy consumption, higher labor requirements, slower throughput, or lack of modern automation and environmental controls.
  3. Economic (External) Obsolescence: Captures value impairment caused by factors external to the machine itself, such as plant underutilization, contraction in domestic product demand, raw-material price shocks, regulatory restrictions, or discontinuation of OEM spare parts.

3. Multiple Value Premises for Banks, Leasing & CFOs

Because lenders, insurers, and CFOs use valuations for distinct decisions, our reports clearly separate Fair Market Value in Continued Use (Going Concern) for IFRS/US GAAP and M&A, Orderly Liquidation Value (OLV) and Forced Liquidation Value (FLV) for bank collateral and leasing credit committees, and Salvage/Scrap Value for retirement planning. Every appraisal includes verified serial-number photography and a full technical specification schedule.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Insurance · Underinsurance · Risk ManagementHow do Replacement Cost New (RCN) insurance appraisals prevent co-insurance penalties and underinsurance in Colombia?
Executive Summary

Under Article 1102 of the Colombian Commercial Code, if a company's or condominium's insured sum falls below actual replacement value at the time of a fire, earthquake, or flood, insurers legally apply the proportional underinsurance rule—slashing claim payouts by 30% to 50% even on partial losses. An independent RCN appraisal eliminates this balance-sheet exposure.

1. The Hidden Financial Trap of Relying on Book Value or Market Value for Insurance

One of the costliest risk-management mistakes made by CFOs, plant managers, and condominium administrators (Propiedad Horizontal under Law 675 of 2001) is setting property insurance limits using historical accounting book value, municipal cadastral value, or real estate market value. Each of those figures is fundamentally wrong for underwriting:

  • Accounting Book Value reflects depreciated historical purchase cost—ignoring inflation, exchange-rate devaluation (USD/COP), and rising steel, concrete, and imported equipment costs.
  • Real Estate Market Value includes the value of the underlying land (which is not destroyed by fire or earthquake and should not be insured), while often understating the true engineering cost to rebuild a specialized facility to current seismic standards (NSR-10).

2. How Proportional Underinsurance (Infraseguro) Works in Practice

Suppose an industrial plant or commercial building in Bogotá or Cali has a true Replacement Cost New of USD $10 million, but is insured for only USD $6 million (60% of value). If a fire causes USD $3 million in partial damage, the insurer does not pay USD $3 million; under Colombia's proportional rule, it pays only 60% of the loss (USD $1.8 million) minus the deductible—leaving the company to absorb over USD $1.2 million out of pocket. Conversely, over-insuring obsolete buildings or insuring land wastes substantial annual premiums.

3. What Our Insurance Valuation Report Delivers

  1. Replacement Cost New (RCN) Excluding Land: Exact current construction cost of foundations, superstructure, MEP installations, elevators, facades, and fire-protection systems rebuilt with modern materials under current NSR-10 building codes, plus debris removal and professional architectural/engineering fees.
  2. Machinery & Equipment RCN Schedules: Itemized replacement schedules in COP and USD covering imported replacement cost, freight, customs duties, and installation—clearly separating insurable plant assets from excluded items.
  3. Actual Cash Value (ACV) & Co-Insurance Compliance: Both Replacement Cost New and Depreciated Replacement Value are reported per building and cost center, giving insurance brokers, risk managers, and reinsurance underwriters an indisputable baseline that accelerates claim settlement and protects corporate liquidity.
Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Aviation · Fine Art · Colombian EmeraldsWhat international protocols govern appraisals of aircraft, helicopters, fine art collections, and GIA-graded Colombian emeralds?
Executive Summary

High-value movable assets—including corporate jets, offshore helicopters, museum-grade Latin American fine art, and investment-grade Colombian emeralds—trade in specialized global markets denominated in USD. Our certified RAA and specialist appraisers combine international price benchmarks, technical logbook audits, and gemological verification.

1. Corporate Aircraft, Helicopters & Fleet Appraisals

Valuing fixed-wing aircraft, executive jets, agricultural planes, or utility helicopters supporting Colombia's oil, mining, and corporate aviation sectors requires rigorous technical and regulatory auditing aligned with Aerocivil (RAC), FAA, EASA, and ICAO guidelines. Our aviation appraisal protocol evaluates:

  • Airframe & Engine Maintenance Status: Exhaustive verification of Time Since New (TSN), Cycles Since New (CSN), Time Since Overhaul (TSOH), and Time Since Hot Section Inspection (TSHSI). Because turbine engines and major structural inspections (C-Check / D-Check) often account for 40% to 70% of an aircraft's total market value, maintenance-adjusted valuation is essential.
  • Airworthiness Directives (ADs), Service Bulletins (SBs) & Traceability: Confirmation of full compliance with OEM directives (Boeing, Airbus, Cessna, Beechcraft, Bell, Airbus Helicopters), back-to-birth traceability for Life Limited Parts (LLPs), and certified AMO/TAR maintenance records.
  • Global Market Benchmarking: Valuation in USD calibrated against Aircraft Bluebook and VREF benchmarks, adjusted for avionics suites (Garmin/Honeywell glass cockpit, TCAS, ADS-B Out), VIP cabin condition, incident history, and Colombian registration/importation status (HK/HJ).

2. Fine Art, Historical Collections & Sculptures

Registered under the specialized RAA category for Fine Art, Goldsmithing & Jewelry, our experts appraise oil paintings, sculptures, lithographs, and private or corporate collections (including Colombian and Latin American masters such as Fernando Botero, Alejandro Obregón, Enrique Grau, Edgar Negret, David Manzur, and Débora Arango). Each report examines uninterrupted provenance, gallery invoices, foundation authenticity certificates, catalogue raisonné inclusion, physical conservation state (craquelure, relining, UV inspection, prior restorations), and homogenized auction comparables from Christie's, Sotheby's, and Phillips.

3. Luxury Jewelry, Precious Metals & Colombian Emeralds

For high jewelry, luxury watches, and investment gems, we verify precious metal fineness (18k/750, 24k gold, platinum) against LBMA spot pricing, grade diamonds using the GIA 4Cs (Carat, Color, Clarity, Cut), and evaluate Colombian emeralds by mining origin (Muzo, Chivor, Coscuez), color saturation, transparency, and clarity-enhancement laboratory certificates—providing rock-solid documentation for all-risk insurance, estate planning, divorce settlements, and collateral financing.
Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Property Tax · Cadastre · IGAC AppealsHow can corporate and foreign property owners appeal an inflated cadastral valuation (Impuesto Predial) in Bogotá, Cali, or Medellín?
Executive Summary

Mass cadastral updates conducted by IGAC and municipal cadastres (Catastro Bogotá, Cali, and Medellín) frequently trigger abrupt 100% to 300% spikes in property tax assessments. Under Colombian law, a cadastral valuation can never exceed 100% of true commercial market value—and a certified RAA commercial appraisal is the decisive legal proof required to win a tax reduction.

1. Understanding the Legal Ceiling on Colombian Property Taxes

Colombia's unified property tax (Impuesto Predial Unificado) is calculated directly from the municipal cadastral valuation. Under Law 14 of 1983, Law 1450 of 2011, and the Multipurpose Cadastre framework (Decree 148 of 2020 and IGAC Resolution 1149 of 2021), the cadastral assessment must legally fall between 60% and 100% of the property's actual commercial market value.

However, because municipal authorities rely on automated mass-appraisal models across broad geoeconomic zones rather than individual interior inspections, commercial warehouses, aging corporate buildings, rural estates, and luxury residences are frequently assessed far above what any buyer would actually pay—creating severe, recurring annual tax overpayments.

2. Valid Technical Grounds for a Cadastral Revision Request

  • Commercial Value Overstatement: Demonstrating through verified market comparables and income capitalization that the official cadastral assessment exceeds 100% of real market value.
  • Physical Area Discrepancies: Proving that the municipal cadastre recorded inflated land or built square meterage compared to approved architectural plans, horizontal property deeds, or topographic surveys.
  • Construction Quality & Structural Condition Errors: Correcting erroneous finish scores, unacknowledged structural deterioration, seismic code (NSR-10) non-compliance, or functional obsolescence in industrial facilities.
  • Zoning & Environmental Restrictions: Documenting buildability limits, river buffer zones (rondas hídricas), heritage protections, or landslide/flood risk designations ignored by mass-appraisal algorithms.

3. Our Proven Administrative Defense Workflow

Goods & Services Consulting S.A.S. prepares a comprehensive Certified Commercial Appraisal under IGAC Resolution 941 of 2026 specifically engineered to meet the evidentiary standards of Unidad Administrativa Especial de Catastro Distrital (UAECD Bogotá), Catastro Cali, Catastro Medellín, and IGAC. Our dossier includes georeferenced photographic proof, statistical comparable matrices, land-use certifications, and formal RAA credentials—enabling our clients and their tax counsel to file timely administrative revision petitions and secure lasting reductions in annual property tax liabilities.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
Timelines · Field Protocol · DocumentsWhat are the turnaround times, field inspection stages, and required documents for a certified appraisal in Colombia?
Executive Summary

Our engagement workflow is engineered for institutional speed without compromising audit or judicial rigor. Standard residential appraisals are delivered in 2 to 4 business days after inspection, commercial properties in 3 to 6 business days, and industrial plants or Oil & Gas portfolios on tailored project timelines.

1. Standard Delivery Turnaround Times

  • Residential Real Estate (Apartments & Homes in Bogotá, Cali, Medellín): 2 to 4 business days following the on-site physical inspection and receipt of baseline legal documents.
  • Commercial Real Estate, Corporate Offices & Logistics Warehouses: 3 to 6 business days, encompassing POT zoning verification, highest-and-best-use analysis, and commercial rent capitalization studies.
  • Industrial Plants, Manufacturing Lines & Heavy Machinery: 5 to 10 business days, covering serial-plate verification, maintenance history review, OEM replacement-cost research, and DRC modeling.
  • Oil & Gas Infrastructure, Multi-Site IFRS Inventories, Aircraft & Business Valuations: 10 to 20 business days (or phased milestones for nationwide multi-location portfolios), incorporating full DCF/WACC financial models and ERP reconciliation files.

2. Four Non-Negotiable Quality Assurance Stages

  1. Stage 1 — Legal & Zoning Pre-Audit: Review of title registry records (ORIP), boundary descriptions, easements, liens, and official municipal POT land-use regulations before field deployment.
  2. Stage 2 — Mandatory On-Site Physical Inspection: Georeferenced photographic survey, area verification, finish and structural condition grading, pathology detection, and serial/tag verification conducted by RAA-accredited personnel.
  3. Stage 3 — Market Intelligence & Econometric Modeling: Collection and depuration of contemporary comparables, outlier filtering, homogenization matrices, and cross-checking across Cost, Market, and Income approaches.
  4. Stage 4 — Senior Committee Review & Certified Issuance: Peer validation by our senior technical committee, verification of all 12 mandatory sections under IGAC Resolution 941 of 2026 (plus USPAP/IFRS disclosures where applicable), digital signature, and delivery in high-resolution PDF and editable executive schedules.

3. Baseline Document Checklist for Real Estate Appraisals

To initiate a real estate valuation smoothly, clients typically provide: (1) an updated Certificado de Tradición y Libertad (ideally issued within the past 30 days), (2) the latest Property Tax bill (Recibo Predial) displaying the cadastral ID/CHIP, (3) a copy of the Public Acquisition Deed, (4) approved architectural plans (for warehouses or commercial buildings), and (5) the Horizontal Property Bylaws (RPH) for condominiums or offices. For rural or industrial properties, water concessions, topographic maps (MAGNA-SIRGAS), and land-use certificates complement the file. If any document is missing, our team assists foreign owners directly in obtaining official copies.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
RAA · Law 1673 · IGAC Res. 941 (2026)What makes an appraisal legally binding before Colombian banks, insurers, courts, and Big Four auditors?
Executive Summary

In Colombia, valuation is a strictly regulated professional activity under Law 1673 of 2013. An appraisal signed by an unlicensed broker or non-registered consultant carries zero legal force before banks, judges, tax authorities, or auditors. Only active RAA-certified appraisers complying with IGAC Resolution 941 of 2026 and General Procedural Code (CGP) rules produce legally binding reports.

1. Mandatory RAA Registration Under Law 1673 of 2013

Colombia's Appraiser Law (Law 1673 of 2013 and Decree 556 of 2014) restricts formal valuation practice to individuals actively inscribed in the Registro Abierto de Avaluadores (RAA), supervised by a recognized self-regulatory entity (ERA). Crucially, RAA accreditation is segmented into 13 specialized asset categories (Urban Real Estate, Rural Real Estate, Fixed & Mobile Machinery, Special Industrial Assets, Intangibles & Businesses, Fine Art & Jewelry, Natural Resources, among others). A real estate appraiser cannot legally sign a machinery or business valuation unless specifically certified in that category.

Every report issued by Goods & Services Consulting S.A.S. attaches the signing appraiser's current RAA certificate in the exact statutory category of the asset, along with clean disciplinary standing verification.

2. Full Compliance with IGAC Resolution 941 of 2026

In 2026, IGAC Resolution 941 modernized Colombia's historical technical standards (previously Resolution 620 of 2008), raising the bar for statistical transparency, mandatory on-site inspection documentation, comparable traceability, and the 12 mandatory content requirements of a commercial appraisal. Non-compliant reports are routinely rejected by Asobancaria credit committees, public agencies, and cadastral authorities—delaying closings and financing disbursements.

3. Judicial Admissibility Under the General Procedural Code (Law 1564 of 2012)

For litigation, arbitration before the Chambers of Commerce (Bogotá, Cali, Medellín), expropriation counter-appraisals (IDU / Metro / 4G highways), corporate shareholder disputes, divorces, or estates, Articles 226 to 235 of the Código General del Proceso (CGP) require an expert witness report (Dictamen Pericial) containing:

  • Sworn Declaration of Impartiality: Formal disclosure under oath confirming total independence and absence of conflicts of interest with any party.
  • Complete Methodological & Mathematical Transparency: Full disclosure of formulas, market sources, comparable adjustments, and supporting appendices so opposing counsel and the judge can verify every calculation.
  • Expert Witness Testimony in Court: Statutory commitment by the signing RAA appraiser to appear at evidentiary hearings and defend the valuation under cross-examination.

With over 20 years of uninterrupted track record (2006–2026) and institutional clients including IGAC, DANE, Grupo Energía Bogotá, OPAIN El Dorado, ANI, and leading multinationals, our reports withstand the highest banking, judicial, and international audit scrutiny.

Need a certified USPAP, IFRS, or RAA valuation on this topic?Request a Senior Appraiser Consultation →
DIRECT SENIOR APPRAISER DESK

Ready for Your Certified Appraisal in Colombia?

Receive a clear technical scope, timeline, and no-obligation fee proposal directly from an RAA and Appraisal Institute certified appraiser.

Senior technical response in under 2 business hours Audit-ready reports for Big Four, U.S. banks, insurers & courts Nationwide coverage from Bogotá D.C., Cali & Medellín

Request Your Quote

Direct connection with a bilingual senior appraiser.

Bogotá D.C. Headquarters

Carrera 15 # 88-21, Office 702 (Chapinero / Chicó)

+57 (317) 639 4990+57 (316) 298 7689

Cali, Valle del Cauca Office

Cra 56 # 2-157, Office 505, Tower 2 · Edificio Sottomonte – Cuarto de Legua

+57 (317) 639 4990(602) 347 2777

Corporate Desk & RFPs

Multinational RFPs, Big Four engagements, banking agreements, and formal proposals:

licitaciones@goodsyservices.com